Understanding Coastal Risk Factors in Cape May
Cape May's picturesque coastal location comes with distinct insurance challenges that homeowners must carefully consider. The combination of salt water exposure, severe weather patterns, and historic architecture creates a unique risk profile that standard homeowners insurance may not adequately address.
Environmental Hazards and Weather Exposure
Living in Cape May means your home faces constant exposure to salt spray, which accelerates deterioration of roofing materials, siding, and metal fixtures. Hurricane season brings significant wind and water damage risks, while nor'easters can cause flooding and structural damage. Additionally, the sandy soil composition can lead to foundation settling and erosion issues over time.
The Atlantic Ocean's proximity means properties are vulnerable to:
- Storm surge and coastal flooding
- High-velocity winds exceeding standard building codes
- Salt water corrosion of exterior materials
- Erosion and property loss from shoreline retreat
Historic Property Considerations
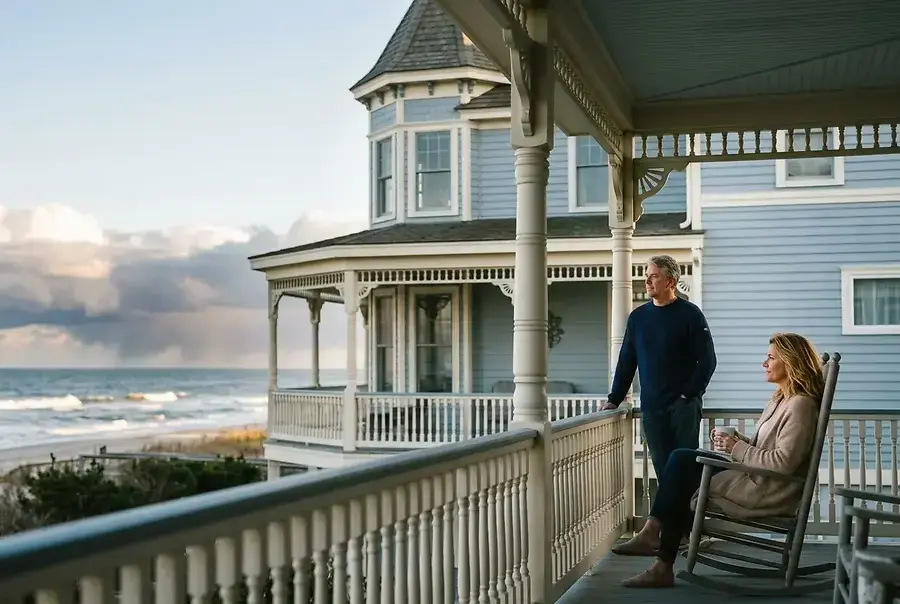
Many Cape May homes are Victorian-era properties with distinctive architectural features that require specialized insurance considerations. Historic homes often have unique construction materials, outdated electrical systems, and irreplaceable design elements that standard policies may not adequately cover. Restoration costs for period-appropriate repairs can significantly exceed modern construction expenses.
Insurance Coverage Types for Historic and Waterfront Homes
Flood Insurance Requirements
Standard homeowners insurance does not cover flood damage, making flood insurance absolutely essential for Cape May properties. The National Flood Insurance Program (NFIP) offers coverage options, though private flood insurance providers may offer more comprehensive protection and competitive rates. Homeowners should evaluate their flood zone designation and consider coverage limits that reflect their property's true replacement value.
Windstorm and Hail Coverage
Cape May's exposure to severe coastal storms necessitates robust windstorm protection. This coverage addresses damage from hurricanes, nor'easters, and other high-wind events. Deductibles for windstorm coverage are typically higher than standard deductibles, often ranging from 5-10% of the home's insured value, so homeowners should understand their financial obligations before a storm strikes.
Specialized Historic Home Insurance
Insurance companies specializing in historic properties understand the unique needs of older homes. These policies typically offer:
- Replacement cost coverage for period-appropriate materials and craftsmanship
- Coverage for architectural details and ornamental features
- Flexibility in repair methods that preserve historical integrity
- Higher coverage limits for specialized restoration work
Coastal Property Insurance Endorsements
Many insurers offer additional endorsements specifically designed for coastal properties. These add-ons provide enhanced protection against salt water damage, erosion, and other coastal-specific risks. Homeowners should discuss available endorsements with their insurance agent to ensure comprehensive coverage.
How to Lower Premiums While Maintaining Adequate Protection
Home Hardening and Mitigation
Insurance companies reward homeowners who take proactive steps to reduce risk. Installing hurricane-resistant windows, reinforcing roof connections, and upgrading to impact-resistant roofing materials can result in significant premium discounts. Additionally, elevating mechanical systems above flood levels and installing storm shutters demonstrates commitment to property protection.
Bundling Policies
Combining homeowners, flood, and windstorm insurance with the same provider often results in substantial discounts. Many insurers offer multi-policy bundles that can reduce overall insurance costs by 10-20%. Shopping around and comparing bundled rates from multiple providers is essential for finding the best value.
Increasing Deductibles Strategically
Homeowners with adequate emergency savings can lower premiums by accepting higher deductibles. However, this strategy requires careful consideration—the savings must be weighed against the financial burden of paying a larger amount out-of-pocket after a loss. A balanced approach involves maintaining reasonable deductibles that don't create financial hardship.
Regular Maintenance and Documentation
Maintaining detailed records of home improvements and regular maintenance demonstrates responsible property ownership. Insurance companies often provide discounts for homes with updated electrical systems, plumbing, roofing, and HVAC systems. Additionally, maintaining a home inventory with photographs and receipts expedites claims processing and ensures proper coverage levels.
Working with Local Insurance Agents
Local insurance professionals understand Cape May's specific risks and can identify coverage gaps that national providers might overlook. They can recommend appropriate coverage limits, explain policy exclusions, and help navigate the claims process when needed. Building a relationship with a knowledgeable local agent provides valuable guidance throughout your homeownership journey.
Conclusion: Making Informed Insurance Decisions
Protecting a Cape May home requires more than standard homeowners insurance. The combination of coastal exposure, historic architecture, and environmental hazards demands a comprehensive, customized insurance strategy. Homeowners should invest time in understanding their specific risks, evaluating available coverage options, and regularly reviewing their policies to ensure adequate protection.
The cost of inadequate insurance pales in comparison to the financial devastation of an uninsured loss. Taking time to secure proper coverage today protects your investment and provides peace of mind for years to come.
By understanding coastal risk factors, selecting appropriate coverage types, and implementing cost-saving measures, Cape May homeowners can achieve the right balance between protection and affordability. Regular policy reviews, staying informed about available discounts, and maintaining open communication with insurance professionals ensure your coverage evolves with your property's needs.