Maximizing Tax Benefits in Commercial Real Estate
Commercial property ownership offers numerous financial advantages, but one of the most significant benefits often goes underutilized: tax deductions. Whether you own office buildings, retail spaces, industrial properties, or multi-unit residential complexes, understanding the tax deductions available to you can dramatically improve your bottom line. The Internal Revenue Service recognizes that property owners incur legitimate business expenses, and many of these expenses can be deducted from your taxable income.
The key to maximizing your tax benefits lies in understanding what qualifies as a deductible expense and maintaining meticulous documentation. Many property owners leave thousands of dollars on the table each year simply because they don't realize certain expenses are tax-deductible. This article explores the essential deductions you should be claiming and provides guidance on maintaining compliance with tax regulations.
Common Tax Deductions Property Owners Often Overlook
Mortgage Interest and Property Taxes
One of the most substantial deductions available to commercial property owners is mortgage interest. If you financed your property purchase, the interest portion of your mortgage payments is fully deductible. This is separate from the principal repayment, which is not deductible. Additionally, property taxes paid to state and local governments are entirely deductible business expenses. These two deductions alone can represent a significant reduction in your taxable income.
Depreciation and Cost Recovery
Depreciation is one of the most powerful deductions available to real estate investors. The IRS allows you to deduct a portion of your property's value each year over its useful life, typically 27.5 years for residential properties and 39 years for commercial properties. This non-cash deduction can substantially reduce your taxable income without affecting your actual cash flow. Cost segregation studies can accelerate depreciation on certain property components, allowing you to claim larger deductions in earlier years.
Operating Expenses and Maintenance
Routine maintenance and repairs are fully deductible business expenses. This includes:
- Painting, repairs, and general upkeep
- Landscaping and grounds maintenance
- HVAC servicing and repairs
- Roof repairs and gutter cleaning
- Parking lot maintenance and snow removal
- Pest control and cleaning services
The distinction between repairs (deductible) and improvements (capitalized) is crucial. Repairs restore property to its original condition, while improvements enhance the property or extend its useful life. Understanding this difference ensures you claim the correct deductions.
Property Management and Professional Fees
If you hire a property management company, those fees are entirely deductible. Similarly, professional services such as accounting, legal advice, and tax preparation related to your commercial property are deductible business expenses. Many owners overlook these deductions, but they can add up significantly over time.
Utilities and Insurance
If you pay for utilities as the property owner, these expenses are deductible. Additionally, property insurance, liability insurance, and loss of rent insurance are all legitimate business deductions. Don't forget to include flood insurance and other specialized coverage your property may require.
Advertising and Tenant Acquisition
Expenses related to advertising vacant units or spaces, including online listings, signage, and broker commissions, are deductible. These costs are necessary to generate rental income and therefore qualify as business expenses.
Travel and Vehicle Expenses
Travel to and from your property for management purposes, inspections, or tenant meetings is deductible. If you use a vehicle for property-related activities, you can deduct either actual expenses or use the standard mileage rate. Keep detailed records of all trips and their business purpose.
Home Office Deduction
If you maintain a dedicated home office for managing your commercial properties, you may qualify for the home office deduction. This can include a portion of rent, utilities, and office supplies. The simplified method allows $5 per square foot, while the regular method requires detailed calculations.
Documentation and Compliance Best Practices for Tax Savings
Maintain Detailed Records
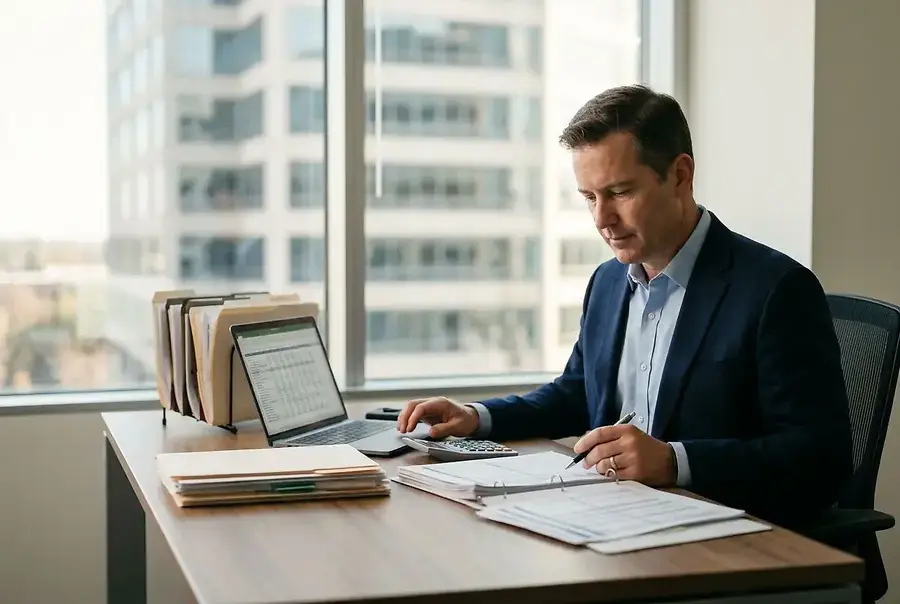
Documentation is the foundation of legitimate tax deductions. The IRS requires that you maintain records supporting all claimed deductions. This includes:
- Receipts and invoices for all expenses
- Bank statements and cancelled checks
- Maintenance logs and repair records
- Mileage logs for vehicle expenses
- Photographs of repairs and improvements
- Contracts with service providers
Organize these documents by category and retain them for at least three to seven years, as the IRS may audit returns from previous years.
Separate Business and Personal Expenses
Maintain separate bank accounts and credit cards for your commercial property business. This clear separation makes it easier to track deductible expenses and demonstrates to the IRS that you're running a legitimate business operation. Commingling personal and business expenses creates confusion and increases audit risk.
Track Capital Improvements
While repairs are immediately deductible, capital improvements must be depreciated over time. Keep detailed records of all improvements, including dates, costs, and descriptions. This information is essential for calculating depreciation and for determining your adjusted basis when you eventually sell the property.
Stay Current with Tax Law Changes
Tax regulations change frequently, and deductions available in one year may be modified or eliminated in subsequent years. Stay informed about changes that affect commercial property owners, and adjust your tax strategy accordingly. Consider subscribing to tax updates or consulting with a tax professional regularly.
Working with Professionals to Optimize Your Tax Strategy
While understanding tax deductions is important, the complexity of commercial real estate taxation makes professional guidance invaluable. Certified Public Accountants (CPAs) and tax attorneys specializing in real estate can identify deductions you might miss and ensure your tax strategy complies with current regulations.
A qualified tax professional can help you:
- Implement cost segregation studies to accelerate depreciation
- Structure your property ownership for maximum tax efficiency
- Navigate complex depreciation rules and recapture provisions
- Plan for capital gains taxes when selling properties
- Ensure compliance with all IRS requirements and reporting obligations
The money you invest in professional tax advice often pays for itself many times over through identified deductions and optimized tax strategies.
By taking advantage of legitimate tax deductions and maintaining proper documentation, commercial property owners can significantly reduce their tax liability and improve their investment returns. The key is understanding what qualifies as a deductible expense, maintaining meticulous records, and working with qualified professionals to optimize your tax strategy. Start reviewing your current expenses today to identify deductions you may have overlooked, and consider consulting with a tax professional to ensure you're maximizing your commercial real estate tax benefits.