Understanding Regional Insurance and Tax Differences
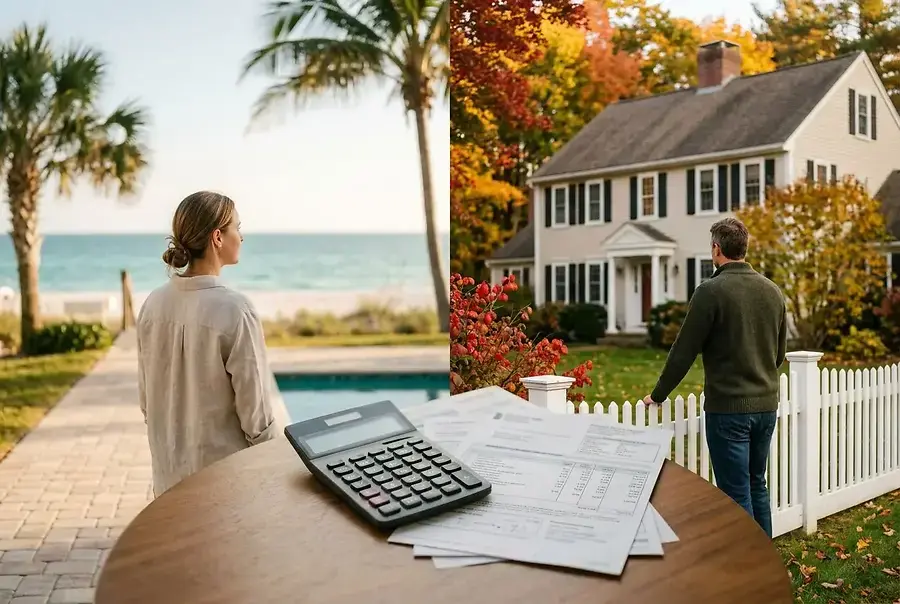
When considering a move to a new state, homeowners often focus on property prices and climate, but two critical financial factors frequently get overlooked: homeowner insurance costs and property taxes. These expenses can significantly impact your long-term housing budget and overall financial well-being. Whether you're contemplating a move from the Northeast to Florida's sunny coast or vice versa, understanding these regional differences is essential for making an informed decision.
Florida's coastal markets, including St. Augustine, Jacksonville, and Palm Coast, have experienced tremendous growth in recent years. Similarly, Connecticut, Rhode Island, and Massachusetts continue to attract homeowners seeking established communities and cultural amenities. However, the financial implications of homeownership differ substantially between these regions, making a detailed comparison invaluable for prospective buyers.
Property Tax Rates: Northeast vs. Florida Coastal Markets
Florida's Property Tax Advantage
One of Florida's most significant advantages for homeowners is its relatively low property tax rates. Florida has no state income tax, which allows the state to generate revenue through property taxes, yet the rates remain competitive. The effective property tax rate in Florida typically ranges from 0.71% to 0.98% of assessed property value, depending on the county.
- St. Augustine: Located in St. Johns County, property taxes average around 0.85% of assessed value
- Jacksonville: Duval County residents pay approximately 0.89% in property taxes
- Palm Coast: Flagler County offers rates around 0.76%, among Florida's lowest
For a $400,000 home in these Florida markets, annual property taxes would typically range from $3,040 to $3,560—a manageable expense for most homeowners.
New England's Higher Property Tax Burden
The Northeast presents a starkly different picture. New England states are known for funding excellent schools and public services through property taxes, resulting in significantly higher rates:
- Connecticut: Effective property tax rates average 2.14% of assessed value, among the nation's highest
- Rhode Island: Property taxes average 1.63% of assessed value
- Massachusetts: Rates hover around 1.23% of assessed value
On that same $400,000 home, New England homeowners would pay between $4,920 and $8,560 annually in property taxes. This represents a difference of $1,880 to $5,520 per year compared to Florida—or $18,800 to $55,200 over a decade.
The Homestead Exemption Factor
Florida offers additional tax relief through its homestead exemption, which reduces the assessed value of primary residences by $50,000. This exemption can save homeowners hundreds of dollars annually. New England states offer limited homestead exemptions, making Florida's advantage even more pronounced for primary residence owners.
Homeowner Insurance Costs and Coverage Variations by Region
Florida's Insurance Challenges
While Florida excels in property tax rates, homeowner insurance presents a different challenge. Coastal Florida communities face elevated insurance costs due to hurricane risk, flooding exposure, and increased claims frequency. Recent years have seen significant rate increases across the state.
In Florida's coastal markets, homeowners can expect:
- St. Augustine: Average annual homeowner insurance costs of $1,500-$2,200 for standard coverage
- Jacksonville: Rates typically range from $1,400-$2,000 annually
- Palm Coast: Insurance costs average $1,600-$2,300 per year
These costs often include separate flood insurance, which is mandatory for properties in flood zones and can add $500-$1,500 annually to your insurance expenses.
New England's Insurance Stability
New England homeowners benefit from lower catastrophic risk exposure. While winter weather poses some challenges, the region doesn't face the same hurricane and flooding threats as coastal Florida. Average homeowner insurance costs in New England are notably lower:
- Connecticut: Average annual premiums of $800-$1,200
- Rhode Island: Typical costs range from $750-$1,100 annually
- Massachusetts: Average premiums of $850-$1,250 per year
Flood insurance is rarely required in inland New England communities, eliminating this additional expense for most homeowners.
Coverage Differences and Considerations
Beyond cost, coverage varies significantly between regions. Florida policies must address wind and hail damage, while New England policies focus on winter weather protection. Florida homeowners should carefully review coverage limits for replacement cost, as rebuilding after hurricane damage can be substantially more expensive than in other regions.
"The combination of lower property taxes and higher insurance costs in Florida creates a complex financial picture that requires careful analysis for each individual homeowner."
Making an Informed Decision on Your Next Home Purchase
The Total Cost of Ownership
When comparing these regions, it's essential to calculate total annual housing costs, not just individual expenses. For a $400,000 home:
- Florida (St. Augustine example): Property taxes ($3,400) + Insurance ($1,800) = $5,200 annually
- New England (Connecticut example): Property taxes ($8,560) + Insurance ($1,000) = $9,560 annually
This represents a potential annual savings of $4,360 in Florida—though individual circumstances vary based on specific location, home value, and coverage needs.
Beyond the Numbers
While financial considerations are crucial, remember that lifestyle, climate preferences, and community amenities also matter significantly. Florida offers year-round warmth and outdoor recreation, while New England provides distinct seasons, cultural institutions, and established neighborhoods. Your decision should balance financial analysis with personal preferences and long-term life goals.
Consider consulting with a local real estate agent and insurance professional in your target area to obtain accurate quotes and understand region-specific factors that might affect your decision. By combining financial analysis with thorough research, you'll be well-positioned to make the best choice for your family's future.