Why Most Homebuyers Underestimate Total Ownership Costs
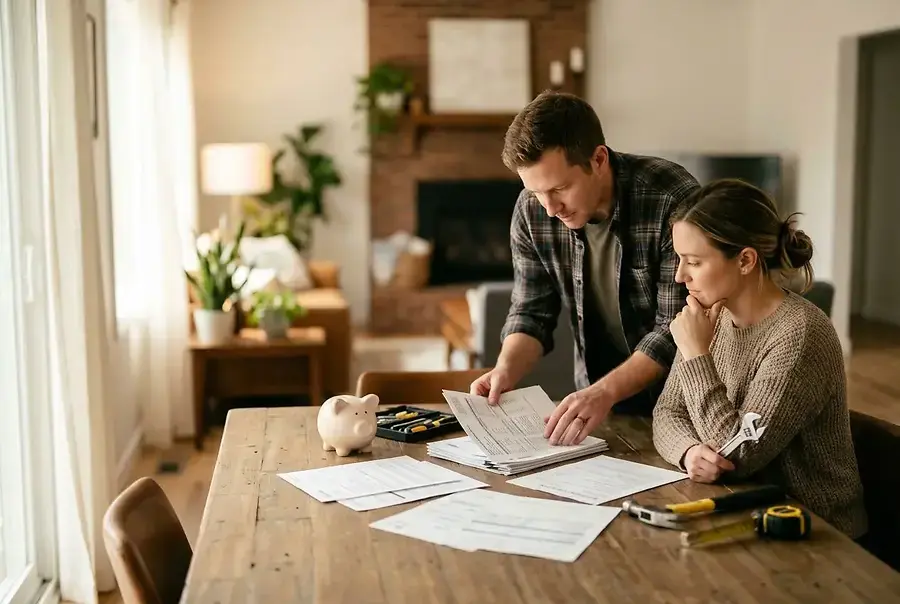
When prospective homeowners calculate whether they can afford a property, they typically focus on one number: the monthly mortgage payment. However, this narrow perspective often leads to financial surprises that can strain budgets and derail long-term financial plans. The reality is that homeownership extends far beyond the principal and interest you pay each month.
Studies show that homeowners spend an average of 1-2% of their home's value annually on maintenance and repairs alone. For a $400,000 home, this translates to $4,000-$8,000 per year in unexpected expenses. When combined with property taxes, insurance, utilities, and HOA fees, the true cost of homeownership can easily exceed mortgage payments by 50% or more.
Understanding these hidden costs before purchasing is crucial for making an informed investment and avoiding financial stress down the road.
Property Taxes, Insurance, and Maintenance: The Big Three Expenses
Property Taxes
Property taxes are often the largest ongoing expense after your mortgage payment. These taxes vary significantly by location, ranging from less than 1% to over 2% of your home's value annually. Unlike mortgage payments, property taxes increase over time as your home's assessed value rises, making them an unpredictable expense that requires careful budgeting.
Before purchasing, research your local tax rates and understand how assessments work in your area. Some regions reassess properties frequently, while others do so less often, affecting the predictability of your tax burden.
Homeowners Insurance
Homeowners insurance is mandatory if you have a mortgage, and costs typically range from $800 to $2,000 annually, depending on your location, home value, and coverage level. Insurance premiums continue to rise due to increased natural disaster risks and inflation. Additionally, if you live in a flood-prone or hurricane-prone area, you may need separate flood or wind insurance, further increasing your expenses.
Maintenance and Repairs
The roof, HVAC system, plumbing, and electrical systems all have finite lifespans. A new roof can cost $10,000-$25,000, while HVAC replacement ranges from $5,000-$15,000. Setting aside funds for these major repairs is essential. Many financial advisors recommend establishing a home maintenance fund equal to 1-2% of your home's purchase price annually.
HOA Fees, Utilities, and Unexpected Repairs: Planning for Hidden Costs
Homeowners Association Fees
If you purchase a property in a community with an HOA, monthly or annual fees can range from $100 to $500+ per month. These fees cover common area maintenance, amenities, and community services. Importantly, HOA fees typically increase annually and are not tax-deductible for most homeowners. Before purchasing, review the HOA's financial statements and reserve fund to ensure the community is well-maintained and fees won't spike unexpectedly.
Utilities and Services
Electricity, water, gas, internet, and trash services add up quickly. In many regions, utility costs have increased significantly, with some homeowners paying $200-$400 monthly depending on climate and home size. Don't overlook these expenses when budgeting for homeownership.
Unexpected Repairs
Even well-maintained homes experience surprises. A burst pipe, foundation crack, or pest infestation can cost thousands to repair. Without an emergency fund, these unexpected expenses can force you into debt or financial hardship. Experts recommend maintaining a separate emergency fund specifically for home-related crises.
Creating a Realistic Budget: Tools and Strategies for Long-Term Financial Planning
Calculate Your True Housing Costs
Use this formula to estimate your total monthly housing expenses:
Total Monthly Housing Cost = Mortgage Payment + Property Taxes + Insurance + HOA Fees + Utilities + Maintenance Reserve
Most financial experts recommend that total housing costs should not exceed 28-30% of your gross monthly income. This includes all expenses mentioned above, not just your mortgage payment.
Build Multiple Reserve Funds
- Maintenance Fund: Set aside 1-2% of your home's value annually for routine maintenance and repairs
- Emergency Fund: Maintain 3-6 months of total housing expenses for unexpected major repairs
- Tax and Insurance Fund: If not escrowed in your mortgage, set aside monthly amounts for these annual expenses
Use Online Calculators and Tools
Numerous online calculators can help you estimate homeownership costs based on your location, home price, and personal circumstances. These tools provide realistic projections and help identify potential budget gaps before you purchase.
Work with Professionals
Real estate agents, mortgage brokers, and financial advisors can provide valuable insights into local costs and help you create a comprehensive budget. A home inspection before purchase can also reveal potential maintenance issues, allowing you to factor these costs into your decision.
Making an Informed Investment in Your Residential Future
Homeownership is a significant financial commitment that extends far beyond monthly mortgage payments. By understanding and budgeting for property taxes, insurance, maintenance, HOA fees, utilities, and unexpected repairs, you can make an informed investment decision and avoid financial stress.
The key to successful homeownership is preparation. Take time to research your local market, calculate realistic costs, and build adequate financial reserves. This proactive approach transforms homeownership from a financial burden into a sound investment in your future.
Remember: the cheapest home isn't always the best investment. The best investment is one you can truly afford, with all costs considered. By planning comprehensively and budgeting wisely, you'll enjoy homeownership without the financial surprises that catch so many buyers off guard.