Beyond the Mortgage Payment
When most people think about buying a home, they focus on the down payment and monthly mortgage. However, the true cost of homeownership extends far beyond these figures. Many first-time buyers are shocked to discover a range of expenses they never anticipated, from property taxes to emergency repairs. Understanding these hidden costs before you purchase is essential for creating a realistic budget and avoiding financial stress down the road.
The difference between the advertised price of a home and the actual cost of ownership can be substantial. In fact, many financial experts suggest that homeowners should budget an additional 1-2% of their home's value annually for all expenses beyond the mortgage payment. For a $300,000 home, this could mean an extra $3,000 to $6,000 per year in unexpected costs.
Property Taxes, Insurance, and HOA Fees Explained
Understanding Property Taxes
Property taxes are one of the most significant ongoing expenses for homeowners, yet many buyers underestimate their impact. These taxes vary dramatically depending on your location, with some states charging significantly more than others. Property taxes are typically calculated as a percentage of your home's assessed value and are used to fund local schools, infrastructure, and public services.
Key points about property taxes:
- They can range from less than 1% to over 2% of your home's value annually
- Tax assessments may increase over time as your property value rises
- Some states offer exemptions or caps for certain homeowners
- Property taxes are often included in your monthly mortgage payment through escrow accounts
Homeowners Insurance Requirements
If you're financing your home with a mortgage, your lender will require homeowners insurance. This insurance protects your property against damage from fire, theft, weather, and other covered events. Unlike property taxes, insurance costs depend on factors such as your home's age, location, construction materials, and your coverage level.
Insurance considerations include:
- Basic homeowners insurance typically costs $800-$1,500 annually, but can be higher in risky areas
- Additional coverage like flood or earthquake insurance may be necessary depending on your location
- Deductibles affect your monthly premiums and out-of-pocket costs
- Shopping around with multiple insurers can save you hundreds of dollars yearly
HOA Fees and Community Assessments
If you're buying a property in a homeowners association, prepare for monthly or annual HOA fees. These fees fund community maintenance, amenities, and services. While HOA communities offer benefits like maintained common areas and sometimes better property values, the fees can be substantial and often increase over time.
Important note: Always review the HOA's financial statements and reserve fund before purchasing. Special assessments for major repairs can sometimes surprise homeowners with unexpected bills.
Maintenance Reserves and Emergency Repairs Every Homeowner Needs
The 1% Rule for Home Maintenance
Financial advisors often recommend setting aside 1% of your home's purchase price annually for maintenance and repairs. For a $300,000 home, this means budgeting $3,000 per year, or $250 per month. This reserve helps you handle everything from routine maintenance to unexpected emergencies without derailing your finances.
A well-maintained home is an investment in your future. Neglecting maintenance today can lead to expensive repairs tomorrow.
Common Expenses Homeowners Face
Understanding typical maintenance costs helps you prepare realistically. Here are expenses many homeowners encounter:
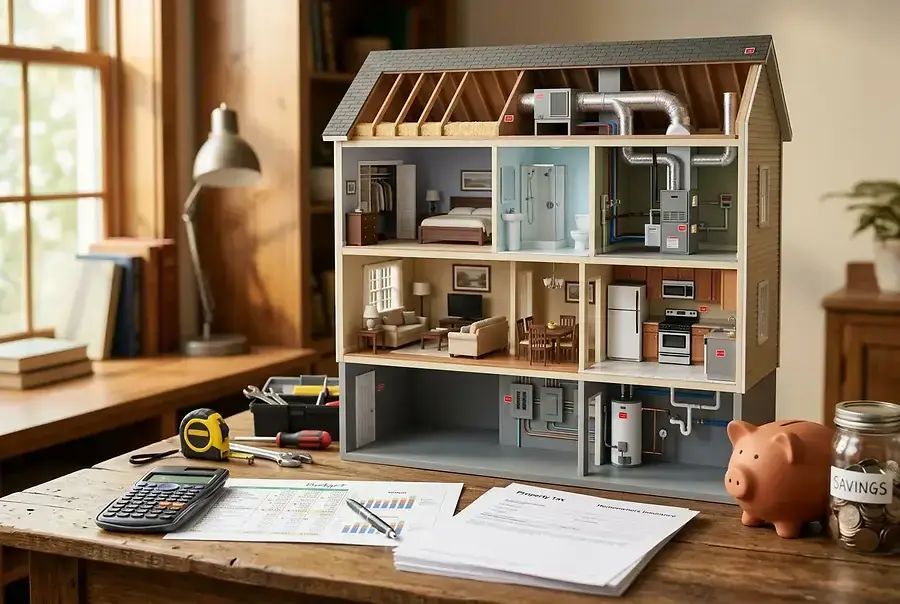
- HVAC systems: Repairs can cost $500-$2,000; replacement runs $5,000-$10,000
- Roof repairs: Patching costs $300-$1,000; full replacement can exceed $15,000
- Plumbing issues: Simple fixes cost $150-$500; major repairs can reach $3,000+
- Water heater replacement: Typically $1,000-$2,500
- Appliance repairs or replacement: $500-$2,000 per appliance
- Exterior maintenance: Painting, siding, and landscaping add up quickly
Building Your Emergency Fund
Beyond regular maintenance, homeowners should maintain an emergency fund specifically for unexpected repairs. A good rule of thumb is to have 3-6 months of your total housing expenses saved. This cushion protects you when major systems fail unexpectedly, such as a furnace breakdown in winter or a foundation issue.
Consider creating a spreadsheet to track your home's major systems and their expected lifespans. This helps you anticipate when replacements might be needed and budget accordingly.
Planning Your Complete Home Budget
Creating a comprehensive home budget requires looking at the complete picture. Start by calculating your total monthly housing costs, including mortgage, property taxes, insurance, HOA fees, and utilities. Then add a percentage for maintenance and repairs. This total should not exceed 28-30% of your gross monthly income according to most lending standards.
Your complete home budget should include:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- HOA fees (if applicable)
- Utilities (electricity, gas, water, sewer)
- Maintenance and repair reserves
- Emergency fund contributions
Before making an offer on a home, request a detailed property disclosure statement and have a professional home inspection completed. These steps reveal potential issues that could become expensive repairs. Additionally, research the neighborhood's property tax rates and typical insurance costs for similar homes.
Working with a financial advisor or mortgage professional can help you understand your specific situation and create a realistic budget. They can provide insights into local costs and help you determine how much home you can truly afford.
Homeownership is a rewarding investment, but it requires careful financial planning. By understanding and preparing for these hidden costs, you'll be better equipped to enjoy your new home without financial stress. Take time to research, plan, and budget comprehensively—your future self will thank you.