Understanding Essential Home Buyer Contingencies
When purchasing a home, one of the most critical aspects of your offer is understanding contingencies. A contingency is a condition that must be met for the sale to proceed, giving you an exit strategy if something goes wrong. Without proper contingencies in place, you could lose your earnest money deposit or face legal complications.
The three primary contingencies that protect home buyers are:
- Inspection Contingency - Allows you to hire a professional inspector to evaluate the property's condition
- Appraisal Contingency - Protects you if the home appraises for less than the purchase price
- Financing Contingency - Ensures your mortgage approval before closing
Each contingency serves a specific purpose in protecting your financial interests. Understanding how they work and when to use them is essential for any home buyer navigating the residential real estate market.
Negotiating Inspection and Appraisal Contingencies
The Inspection Contingency Advantage
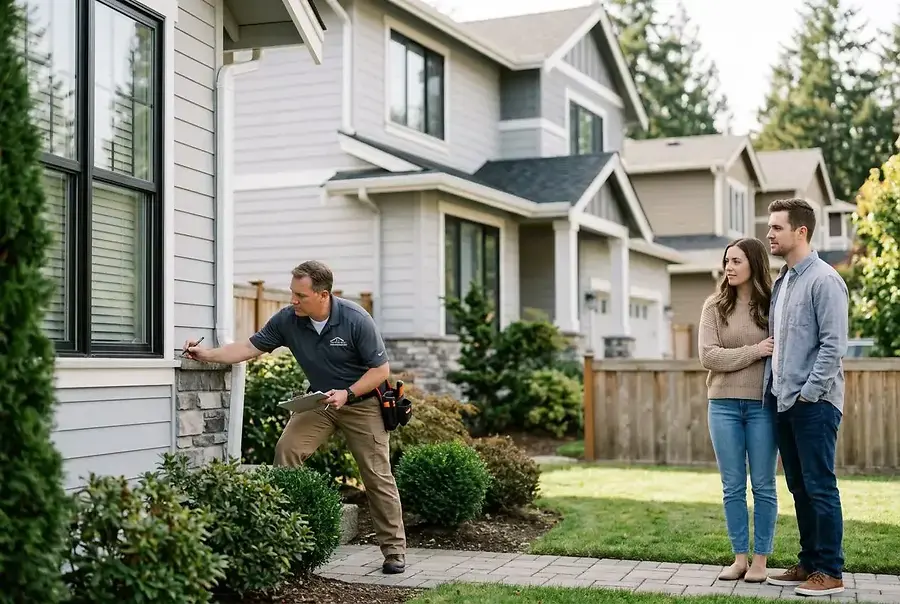
The inspection contingency is your opportunity to discover hidden problems before committing to the purchase. During the inspection period—typically 7-10 days—a licensed inspector will examine the property's structural integrity, electrical systems, plumbing, HVAC, roof, and other critical components.
Key points to negotiate:
- Ensure the inspection period is long enough to complete a thorough evaluation
- Clarify who pays for repairs—you, the seller, or a shared cost arrangement
- Establish a deadline for requesting repairs or renegotiating terms
- Determine your right to walk away if major issues are discovered
If the inspection reveals significant problems, you have three options: request the seller make repairs, ask for a credit toward closing costs, or withdraw your offer without losing your earnest money deposit.
Protecting Yourself with Appraisal Contingencies
An appraisal contingency protects you from overpaying for a property. Your lender will order an appraisal to determine the home's fair market value. If the appraisal comes in lower than your agreed purchase price, this contingency allows you to renegotiate or cancel the contract.
Example: You offer $350,000 for a home, but the appraisal comes back at $330,000. With an appraisal contingency, you can request the seller lower the price or walk away from the deal.
When negotiating this contingency, ensure your contract specifies:
- The timeframe for the appraisal to be completed
- What happens if the appraisal is lower than the purchase price
- Whether you'll cover the appraisal cost if you withdraw
- Your right to challenge the appraisal if you believe it's inaccurate
Financing Contingencies and Closing Protection
Understanding Financing Contingencies
A financing contingency makes your offer conditional upon securing a mortgage loan. This is crucial because it protects you if your lender denies your application or if you can't secure financing at the agreed-upon terms.
Important elements to include:
- The loan amount and type (conventional, FHA, VA, USDA)
- The maximum interest rate you'll accept
- The timeframe for loan approval (typically 21-45 days)
- Your obligation to provide requested documentation promptly
- Clear terms for what happens if financing falls through
Without a financing contingency, you could lose your earnest money if your loan is denied, even through no fault of your own.
Additional Closing Protection Strategies
Beyond the three primary contingencies, consider negotiating additional protections:
Title Contingency: Ensures the seller has clear ownership and the right to sell the property. This protects you from inheriting liens or ownership disputes.
Walk-Through Contingency: Allows you to inspect the property one final time before closing to confirm agreed-upon repairs were completed and the property is in the expected condition.
HOA Contingency: For condos or community properties, this contingency allows you to review homeowners association documents and financials before committing.
Pro Tip: Always include a contingency clause that allows you to terminate the contract if the seller fails to disclose known defects or if undisclosed issues are discovered during inspection.
Conclusion: Making Confident Purchase Decisions
Home buyer contingencies are not obstacles to the sale—they're essential protections that give you peace of mind throughout the purchasing process. By understanding and properly negotiating inspection, appraisal, and financing contingencies, you safeguard your investment and maintain flexibility if problems arise.
The key to successful contingency negotiation is being informed, clear about your needs, and willing to walk away if terms aren't favorable. Work closely with your real estate agent and attorney to ensure all contingencies are properly documented and that you understand your rights and obligations.
Remember, the strongest negotiating position is one where you're prepared to walk away. When sellers know you have proper contingencies in place and won't be pressured into a bad deal, they're often more willing to negotiate reasonable terms. This approach leads to confident, protected home purchases that serve your interests for years to come.