Understanding the Home Appraisal Process and Its Impact on Your Sale
A home appraisal is an independent, professional assessment of your property's market value. When you're selling your home, the appraisal plays a critical role in the transaction. Lenders require appraisals to ensure the property is worth the loan amount they're willing to provide, which directly affects whether a buyer can secure financing.
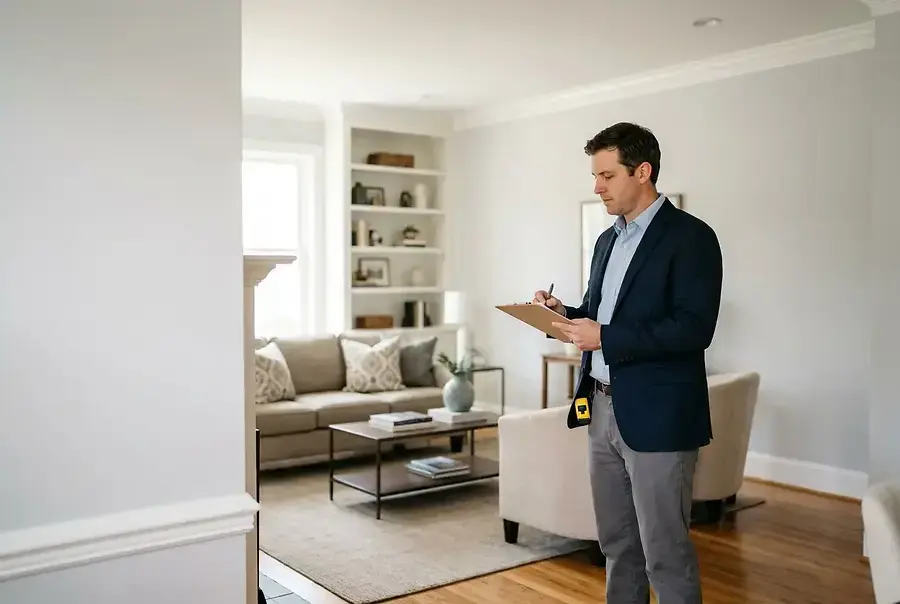
The appraisal process typically begins once an offer is accepted on your home. A licensed appraiser, selected by the lender, will schedule a visit to evaluate your property. This assessment usually takes 1-2 hours, though the appraiser may spend additional time researching comparable sales and market data. The final appraisal report is then submitted to the lender, who uses it to determine the loan-to-value ratio.
Why does this matter for sellers? If the appraisal comes in lower than the agreed-upon purchase price, the buyer may struggle to secure financing, potentially jeopardizing the entire sale. Understanding this process and preparing accordingly can help protect your transaction and ensure your home receives a fair valuation.
Key Factors Appraisers Evaluate in Residential Properties
Professional appraisers follow a systematic approach when assessing residential properties. They examine both the physical characteristics of your home and the broader market context to determine value.
Physical Property Features
- Structural integrity: The foundation, roof, walls, and overall construction quality are fundamental to the appraisal.
- Square footage and layout: Appraisers measure the home's size and evaluate how functional the floor plan is.
- Age and condition: Newer homes or recently updated properties typically appraise higher than older, neglected ones.
- Systems and appliances: HVAC, plumbing, electrical systems, and kitchen appliances are assessed for functionality and age.
- Exterior condition: Landscaping, siding, windows, doors, and overall curb appeal significantly influence the appraisal.
Location and Market Factors
Appraisers also consider the neighborhood and broader market conditions. They evaluate proximity to schools, shopping, employment centers, and public transportation. They assess the overall desirability of the area and compare your home to recently sold properties in the same neighborhood with similar characteristics.
Comparable Sales Analysis
One of the most important aspects of an appraisal is the comparable sales analysis. Appraisers research recent sales of similar homes in your area to establish a baseline value. They adjust for differences in size, condition, age, and features to arrive at an estimated value for your property.
Preparing Your Home to Support a Strong Appraisal Outcome
While you cannot control market conditions or the appraiser's methodology, you can take steps to present your home in the best possible light.
Curb Appeal Matters
First impressions are lasting. Invest in your home's exterior by maintaining the lawn, trimming bushes, painting the front door, and ensuring the entryway is clean and welcoming. A well-maintained exterior signals to the appraiser that the entire property has been cared for properly.
Interior Cleanliness and Organization
A clean, organized home allows the appraiser to easily assess the property's condition. Deep clean before the appraisal appointment, declutter rooms, and ensure all systems are accessible for inspection. A tidy home creates a positive impression and helps the appraiser focus on the property's features rather than maintenance issues.
Document Recent Improvements
Compile documentation of any recent renovations, repairs, or upgrades you've made. This might include receipts for a new roof, kitchen remodel, bathroom updates, or HVAC system replacement. Providing this information helps the appraiser understand the true condition and value of your improvements.
Address Obvious Issues
Before the appraisal, fix any obvious problems that would negatively impact the assessment. This includes leaky faucets, broken windows, damaged siding, or malfunctioning appliances. You don't need to undertake major renovations, but addressing visible defects prevents unnecessary deductions from the appraisal value.
Provide Relevant Information
When the appraiser arrives, be available to answer questions and provide information about your home. Share details about recent upgrades, energy-efficient features, or unique amenities that might not be immediately obvious. This context helps the appraiser make informed decisions about your property's value.
What to Do If Your Appraisal Comes in Lower Than Expected
Receiving a low appraisal can be disappointing, but it's not necessarily the end of the road. You have several options to address the situation.
Request an Appraisal Review
If you believe the appraisal is inaccurate, you can request a review or challenge. Gather evidence of comparable sales that support a higher value, recent improvements you've made, or errors in the appraiser's report. Present this information professionally to the lender or appraiser for reconsideration.
Negotiate with the Buyer
A low appraisal doesn't automatically mean the deal falls apart. You and the buyer can renegotiate the purchase price to align with the appraised value. Alternatively, you might offer to cover part of the difference or make concessions on closing costs.
Request a Second Appraisal
In some cases, you can request a second appraisal from a different licensed appraiser. If the second appraisal comes in higher, you may be able to use that value instead. However, this option depends on your lender's policies and may involve additional costs.
Improve and Re-List
If the appraisal gap is significant and negotiations stall, you might consider withdrawing the listing, making improvements, and re-listing your home at a later date when market conditions may be more favorable.
Understand the Buyer's Position
Remember that the buyer's lender won't finance more than the appraised value. If the appraisal is low, the buyer may need to bring additional cash to the closing table or walk away from the deal. Understanding this dynamic helps you approach negotiations more realistically.
Final Thoughts: Home appraisals are a standard part of the real estate transaction process. By understanding how they work, preparing your property thoughtfully, and knowing your options if challenges arise, you can navigate the appraisal process with confidence and protect your home sale.