Understanding Property Appraisals and Why They Matter for Buyers
A property appraisal is an independent assessment of a home's market value conducted by a licensed professional appraiser. For residential buyers, understanding appraisals is crucial because they directly influence your ability to secure financing and the terms of your mortgage.
When you apply for a mortgage, your lender requires an appraisal to ensure the property's value supports the loan amount you're requesting. Think of it as the lender's way of protecting their investment. The appraiser examines the property's condition, location, size, and comparable sales in the area to determine its fair market value.
Why Appraisals Matter
- Loan Protection: Lenders use appraisals to confirm they're not lending more money than the property is worth.
- Purchase Negotiation: An appraisal can provide leverage in negotiations if the value comes in lower than the agreed purchase price.
- Investment Confidence: Knowing the true value of your investment helps you make informed financial decisions.
- Insurance Purposes: Accurate appraisals help determine appropriate homeowners insurance coverage.
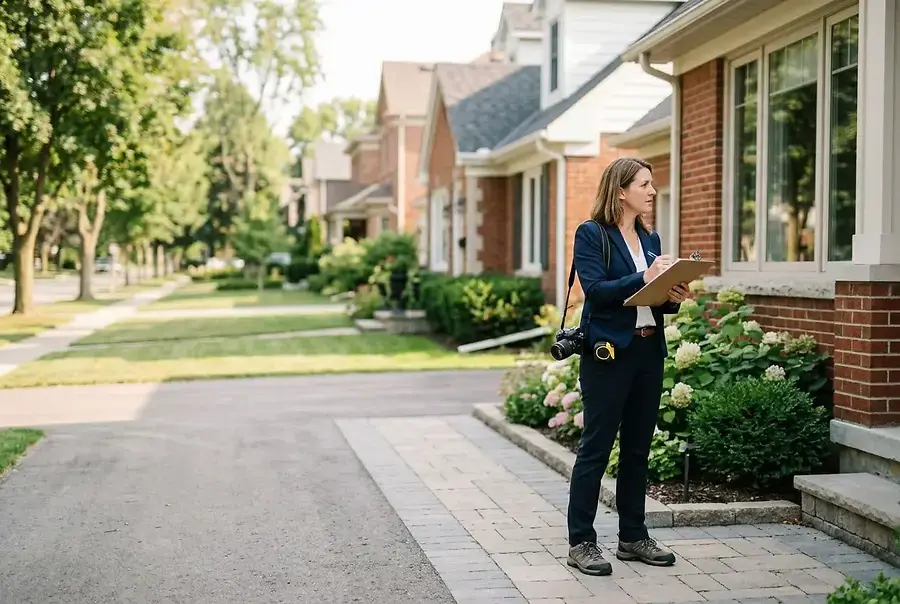
The appraisal process typically takes 7-10 business days from the time your lender orders it. During this time, the appraiser will visit the property, take measurements, photograph key features, and research comparable properties in your neighborhood.
How Appraisals Affect Your Mortgage Approval and Purchase Timeline
The appraisal result can significantly impact your mortgage approval and the overall timeline of your home purchase. Understanding this relationship helps you prepare for potential scenarios.
When the Appraisal Meets or Exceeds the Purchase Price
This is the ideal scenario. When the appraised value equals or exceeds your agreed purchase price, your mortgage approval typically proceeds smoothly. Your lender will approve the loan amount you requested, and you can move forward to closing without complications.
The Impact on Your Timeline
A favorable appraisal keeps your purchase timeline on track. Most home purchases close within 30-45 days from the offer acceptance date. An appraisal that supports your loan amount eliminates potential delays and allows you to proceed to the final stages of the transaction.
Appraisal Contingencies
Many purchase agreements include an appraisal contingency, which protects you as a buyer. This clause allows you to renegotiate or withdraw from the purchase if the appraisal comes in significantly lower than the agreed price. Always review your contingency terms carefully with your real estate agent or attorney.
Pro Tip: Request a copy of the appraisal report from your lender. Reviewing the appraiser's findings helps you understand how your property was valued and identify any errors that might need correction.
Tips for Preparing Your Home for a Successful Appraisal Process
While you cannot control the appraiser's final valuation, you can take steps to ensure your property is presented in the best possible light during the appraisal inspection.
Before the Appraisal Visit
- Clean and Declutter: A well-maintained appearance creates a positive impression. Clean windows, landscaping, and entryways matter.
- Make Minor Repairs: Fix obvious issues like broken fixtures, cracked tiles, or damaged paint. These small details influence the appraiser's perception of overall maintenance.
- Document Improvements: Gather receipts and documentation for any recent renovations or upgrades. This information helps the appraiser understand the property's true condition and value.
- Ensure Access: Make sure all areas of the property are accessible, including the attic, basement, and crawl spaces. Appraisers need to inspect these areas thoroughly.
- Prepare Comparable Sales Information: While the appraiser conducts their own research, having information about recent comparable sales in your area can be helpful.
During the Appraisal
You don't need to be present during the appraisal, but if you are, be helpful without being intrusive. You can answer questions about recent improvements or provide context about the neighborhood, but avoid trying to influence the appraiser's assessment.
What Appraisers Look For
Understanding what appraisers evaluate helps you prepare effectively:
- Property size and square footage
- Number of bedrooms and bathrooms
- Overall condition and age of the structure
- Quality of construction and materials
- Functional layout and flow
- Neighborhood characteristics and location
- Recent comparable sales in the area
- Market trends and economic factors
What to Do If Your Appraisal Comes in Lower Than Expected
A low appraisal can be stressful, but it's not necessarily the end of your home purchase. You have several options to consider.
Request an Appraisal Review
If you believe the appraisal is inaccurate, you can request a review. Contact your lender and ask about their appraisal review process. You may be able to provide additional information or comparable sales data that the appraiser missed. Some lenders allow a second appraisal if you dispute the first one.
Renegotiate the Purchase Price
A low appraisal gives you leverage in negotiations. You can ask the seller to reduce the purchase price to match the appraised value. Many sellers are willing to negotiate rather than lose the sale, especially if the appraisal gap is relatively small.
Increase Your Down Payment
If you have additional funds available, you can increase your down payment to cover the difference between the appraised value and the purchase price. This option allows you to proceed with the purchase without renegotiating.
Walk Away from the Deal
If your purchase agreement includes an appraisal contingency and you're uncomfortable proceeding, you have the right to withdraw from the purchase. While disappointing, this protects you from overpaying for a property.
Appeal to Your Lender
Some lenders may approve a loan amount slightly above the appraised value if your credit is strong and you have a substantial down payment. This is less common but worth discussing with your lender if other options aren't viable.
Important: Never ignore a low appraisal or proceed without addressing it. A low appraisal indicates the property may be overpriced, and proceeding without resolution could result in negative equity from day one of ownership.
Learning from the Experience
Whether your appraisal comes in as expected or surprises you, use it as a learning opportunity. Understanding your property's true market value helps you make informed decisions about your investment and future financial planning.
Remember, appraisals are just one part of the home buying process. By understanding how they work and preparing appropriately, you can navigate this important step with confidence and protect your interests as a residential buyer.