Why Flood Risk Matters for Trumbull Homeowners
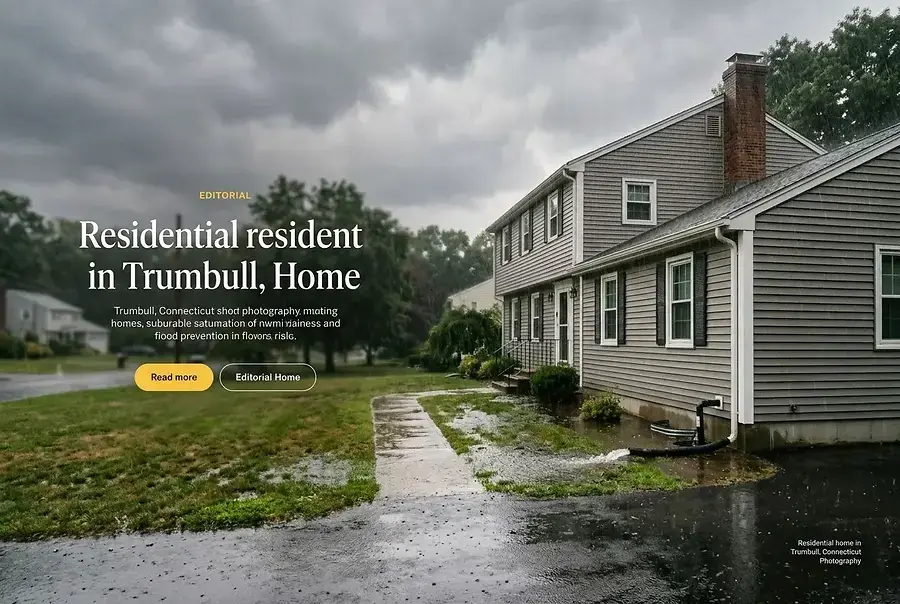
Living in Trumbull, Connecticut offers many advantages, but homeowners must understand the unique challenges that come with the region's geography and climate. Flooding is a serious concern that can devastate properties and finances, yet many residents underestimate their vulnerability to water-related damage.
Connecticut experiences significant rainfall throughout the year, and Trumbull's proximity to coastal areas and local waterways increases flood risk. Whether from heavy storms, overflowing rivers, or coastal surge, water damage can cost homeowners tens of thousands of dollars in repairs. Standard homeowners insurance typically does not cover flood damage, leaving many properties unprotected.
Understanding your flood risk is the first step toward protecting your investment. By taking proactive measures and securing appropriate insurance coverage, you can safeguard your home and maintain peace of mind.
Assessing Your Property's Flood Zone and Risk Level
Understanding FEMA Flood Maps
The Federal Emergency Management Agency (FEMA) provides detailed flood maps that categorize properties into different risk zones. These maps are essential tools for understanding your home's vulnerability. High-risk zones (Special Flood Hazard Areas) require mandatory flood insurance if you have a mortgage, while moderate and low-risk areas may still benefit from coverage.
To find your property's flood zone:
- Visit the FEMA Flood Map Service Center online
- Enter your address to view your specific flood zone designation
- Review the map details and elevation data
- Contact your local Trumbull assessor's office for additional information
Local Risk Factors
Beyond FEMA designations, several local factors affect your flood risk:
- Proximity to waterways: Properties near the Pequonnock River, Mill River, or coastal areas face elevated risk
- Elevation: Lower-lying properties are more susceptible to flooding
- Drainage systems: Areas with poor drainage infrastructure experience more frequent water accumulation
- Historical flooding: Check local records for past flood events in your neighborhood
- Development patterns: Increased impervious surfaces in developed areas can worsen drainage issues
Professional Assessment
Consider hiring a professional flood risk assessor to evaluate your specific property. These experts can identify vulnerabilities, recommend mitigation measures, and help you understand your true risk level. This investment often pays for itself through better insurance rates and targeted home improvements.
Flood Insurance Options and Coverage for Connecticut Residents
National Flood Insurance Program (NFIP)
The NFIP is the primary source of flood insurance for most Americans. This federally-backed program offers coverage regardless of your property's flood risk level, making it accessible to all homeowners. NFIP policies typically cover:
- Building coverage up to $250,000
- Personal property coverage up to $100,000
- Protection against rising water from any source
Important note: NFIP policies include a 30-day waiting period before coverage begins, so don't delay in obtaining protection.
Private Flood Insurance
Private insurers now offer flood insurance policies that may provide advantages over NFIP coverage. These options often include:
- Higher coverage limits
- Lower premiums in some cases
- More flexible deductible options
- Faster claims processing
- Additional coverage options like loss of use
Compare quotes from multiple private insurers to find the best value for your situation.
Coverage Considerations
When selecting flood insurance, consider these important factors:
- Building vs. contents: Ensure you have adequate coverage for both your structure and personal belongings
- Deductibles: Higher deductibles lower premiums but increase out-of-pocket costs during claims
- Replacement cost vs. actual cash value: Replacement cost coverage is more expensive but provides better protection
- Mitigation credits: Some insurers offer discounts for flood-resistant improvements like elevated utilities or sump pumps
Mitigation Measures to Reduce Risk
Beyond insurance, implementing flood mitigation strategies can protect your home and potentially lower insurance costs:
- Elevate utilities: Move HVAC systems, water heaters, and electrical panels above potential flood levels
- Install sump pumps: Basement sump pumps can prevent water accumulation
- Improve drainage: Grade soil away from your foundation and maintain gutters and downspouts
- Seal foundation cracks: Waterproof your basement to prevent seepage
- Install flood vents: Allow water to flow through crawl spaces rather than accumulate
- Use flood-resistant materials: When renovating, choose materials that withstand water exposure
Making Informed Decisions to Safeguard Your Home
Protecting your Trumbull home from flood risk requires a comprehensive approach combining awareness, assessment, and action. Start by determining your flood zone and understanding your specific risk level, then evaluate your insurance options carefully.
Don't wait for a flood warning to secure protection. The time to act is now, while you have options and time to make informed decisions.
Review your current homeowners insurance policy and confirm whether flood coverage is included. If not, obtain quotes for both NFIP and private flood insurance. Consider implementing mitigation measures that fit your budget and property characteristics.
Finally, stay informed about local flood risks and weather patterns. Sign up for emergency alerts from Trumbull's emergency management office and maintain awareness of seasonal flood risks. By taking these steps, you'll protect your property investment and ensure your family's safety and security.
Your home is likely your most valuable asset. Investing time and resources in flood protection is an investment in your family's future and financial security.