Understanding Residential Property Tax Deductions
As a homeowner, you have access to numerous tax deductions that can substantially reduce your annual tax liability. The Internal Revenue Service recognizes that homeownership comes with significant expenses, and many of these costs are deductible. Understanding which deductions apply to your situation is the first step toward maximizing your tax benefits.
The most well-known deduction for homeowners is the mortgage interest deduction. If you have a mortgage on your primary residence, you can deduct the interest you pay on loans up to $750,000. This deduction applies to both first and second homes, making it one of the most valuable tax breaks available to property owners.
Another major deduction is property taxes. Homeowners can deduct state and local property taxes paid on their residential property. However, there is a combined cap of $10,000 per year for all state and local taxes, including property taxes, income taxes, and sales taxes. This limitation is important to keep in mind when calculating your total deductible expenses.
Home Improvement Deductions
Not all home improvements are tax-deductible, but certain upgrades that improve your home's value or extend its useful life may qualify. Capital improvements—such as adding a new roof, installing solar panels, or upgrading your HVAC system—can increase your home's basis and reduce capital gains taxes when you sell. These improvements must add value to your home, prolong its life, or adapt it to new uses.
It's crucial to distinguish between repairs and improvements. Repairs maintain your home's current condition and are generally not deductible. Improvements, on the other hand, enhance your property's value and may provide tax benefits.
Common Deductions Homeowners Overlook
Many homeowners miss out on valuable deductions simply because they're unaware of them. Here are some commonly overlooked tax breaks:
Energy-Efficient Home Improvements
If you've installed energy-efficient upgrades like solar panels, geothermal heat pumps, or energy-efficient windows, you may qualify for the Residential Energy Credit. This credit can cover a significant portion of your installation costs, providing substantial tax savings. These improvements must meet specific energy efficiency standards to qualify.
Home Office Deductions
If you use a portion of your home exclusively for business purposes, you may deduct expenses related to that space. This includes a percentage of your mortgage interest or rent, property taxes, utilities, insurance, and maintenance costs. The simplified method allows you to deduct $5 per square foot of home office space, up to 300 square feet.
Medical Expense Home Modifications
Homeowners who make modifications to accommodate medical conditions or disabilities may deduct these expenses. Examples include:
- Installing grab bars and handrails
- Widening doorways for wheelchair accessibility
- Installing ramps or elevators
- Modifying bathrooms for accessibility
These modifications must be medically necessary and not increase your home's value to qualify for the deduction.
Mortgage Points
When you purchase a home, you may pay discount points to lower your interest rate. These points are generally deductible in the year you pay them, though there are specific rules for refinanced mortgages. Each point typically costs 1% of your loan amount and can save you thousands in interest over the life of your loan.
Home Security Systems
If you use your home for business purposes, a portion of your home security system costs may be deductible. However, if the system is purely for personal security, it's not deductible.
Documentation and Record-Keeping for Tax Benefits
Claiming tax deductions requires proper documentation. The IRS may request evidence to support your claims, so maintaining detailed records is essential.
What to Keep on File
Maintain organized records of:
- Mortgage statements showing interest paid and property taxes
- Receipts and invoices for home improvements and repairs
- Utility bills if claiming home office deductions
- Contractor estimates and invoices for capital improvements
- Before and after photos documenting home improvements
- Permits and inspection reports for major renovations
- Energy audit reports for efficiency upgrades
Organizing Your Records
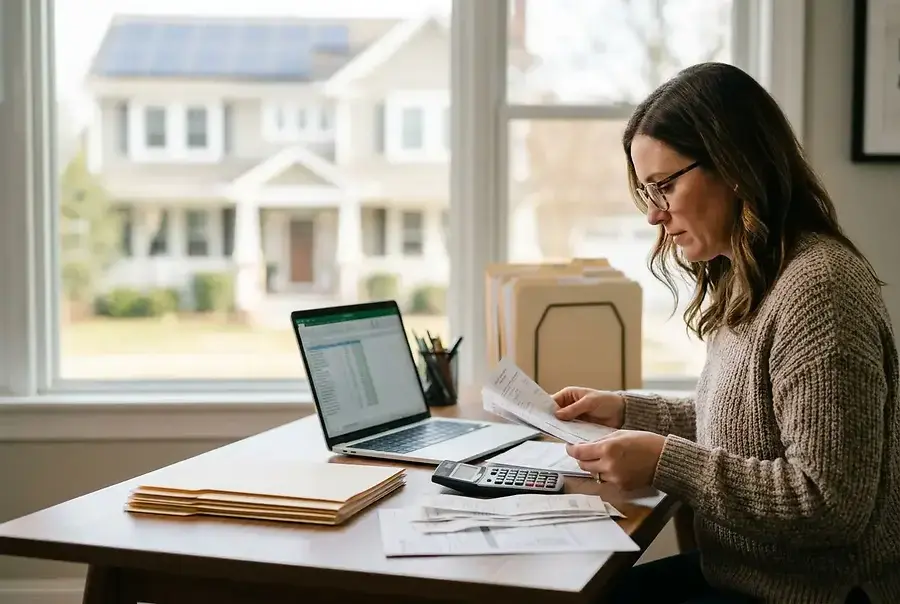
Create a filing system that separates records by category—mortgage documents, improvements, repairs, and utilities. Digital copies are acceptable, but keep originals for at least three to seven years. Many homeowners use spreadsheets or dedicated apps to track expenses throughout the year, making tax preparation much easier.
Pro Tip: Keep receipts and documentation for at least seven years, as the IRS can audit returns from previous years if they suspect underreporting of income or overstating of deductions.
Working with a Tax Professional
Given the complexity of tax deductions, consulting with a qualified tax professional or CPA is highly recommended. They can help you identify deductions you might miss and ensure your documentation meets IRS requirements. The cost of professional tax preparation often pays for itself through the deductions they help you claim.
Conclusion: Maximizing Your Homeowner Tax Advantages
Residential property tax deductions represent significant opportunities to reduce your annual tax burden. By understanding which deductions apply to your situation, staying aware of commonly overlooked breaks, and maintaining meticulous records, you can maximize your tax savings.
The key to successfully claiming homeowner deductions is organization and documentation. Keep detailed records of all expenses, maintain receipts, and consider working with a tax professional to ensure you're taking advantage of every deduction available to you. Your home is likely your largest investment—make sure you're getting the full tax benefits that come with homeownership.
Remember that tax laws change periodically, so it's worth reviewing your deductions annually and consulting with a tax advisor to stay current on any new opportunities or limitations that may affect your situation.