Introduction: The Rent vs. Buy Decision in Today's North Texas Market
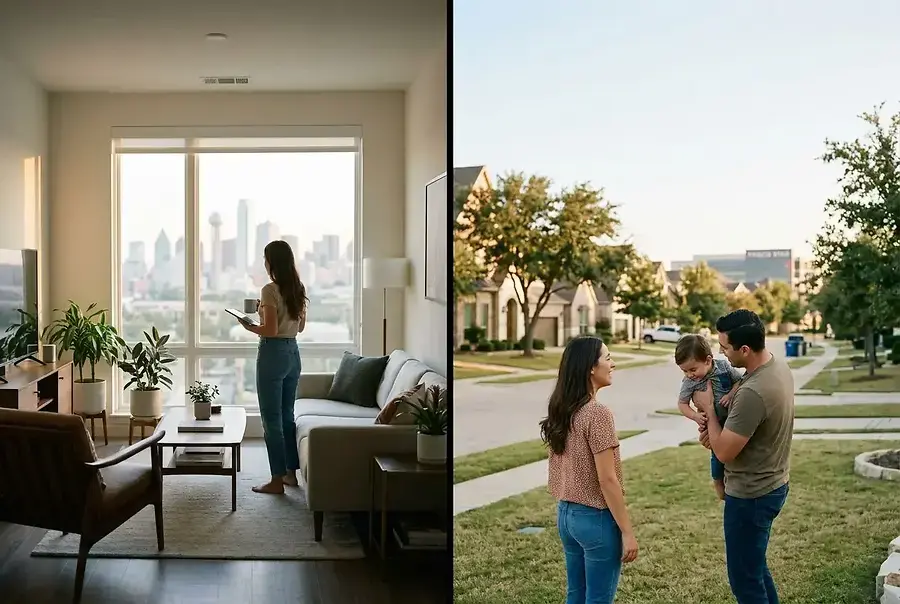
The decision to rent or buy a home is one of the most significant financial choices you'll make. In North Texas—a region encompassing vibrant communities like McKinney, Plano, Dallas, Allen, Frisco, and Prosper—this decision carries unique considerations. The North Texas market has experienced substantial growth, attracting young professionals, families, and retirees alike. Whether you're relocating for work, starting a family, or seeking a change of scenery, understanding the financial and personal implications of renting versus buying is essential.
This guide breaks down the key factors to help you determine which option aligns best with your financial situation and lifestyle goals.
Financial Comparison: Breaking Down Monthly Costs and Long-Term Wealth Building
The Monthly Cost Analysis
When comparing renting and buying, the monthly payment is often the first consideration. However, the full picture extends far beyond rent or mortgage payments.
- Renting Costs: Your monthly rent covers housing, and landlords typically handle major maintenance. However, renters should budget for renter's insurance (usually $10-20 monthly) and utilities not included in rent.
- Buying Costs: Mortgage payments are just the beginning. Homeowners must also account for property taxes, homeowners insurance, HOA fees (if applicable), maintenance reserves, and utilities. In North Texas, property taxes average 1.6-1.8% of home value annually.
Example: A $350,000 home in Frisco with a 20% down payment results in a $280,000 mortgage. At current rates, your monthly payment might be $1,800-$2,000, plus $400-$500 in property taxes, $150-$200 in insurance, and $200-$300 in maintenance reserves—totaling $2,550-$3,000 monthly.
Long-Term Wealth Building
Renting provides flexibility but builds no equity. Each payment goes to your landlord. Buying, conversely, builds equity with every mortgage payment. Over 30 years, this difference becomes substantial.
Wealth Building Advantage: After 10 years of homeownership, you've paid down principal and likely benefited from home appreciation. North Texas has historically appreciated 3-5% annually. A $350,000 home could be worth $450,000-$550,000 in a decade, and you've built significant equity.
"Homeownership is a powerful wealth-building tool, but only if you plan to stay long enough to recoup closing costs and benefit from appreciation."
Break-Even Analysis
Buying involves upfront costs: down payment, closing costs (2-5% of purchase price), and inspection fees. These typically total $15,000-$25,000 for a $350,000 home. You generally need to stay 5-7 years to break even on these costs through equity building and appreciation.
If you're uncertain about your long-term plans, renting may be the smarter financial choice.
Lifestyle and Flexibility Factors: Which Option Aligns With Your Life Stage
Renting: Flexibility and Simplicity
Renting offers distinct lifestyle advantages:
- Flexibility: Lease terms typically run 12 months, allowing you to relocate if your job changes or life circumstances shift.
- Maintenance-Free Living: Landlords handle repairs, replacements, and major maintenance—no surprise $5,000 roof repairs.
- Predictable Costs: Your rent remains stable during your lease term, making budgeting straightforward.
- Ideal For: Young professionals, frequent movers, those with uncertain career paths, and people who prefer minimal responsibility.
Buying: Stability and Control
Homeownership provides different lifestyle benefits:
- Stability and Control: You control your living space—paint colors, renovations, and long-term improvements are yours to decide.
- Community Roots: Buying encourages deeper community involvement and long-term planning.
- Family-Friendly: Families often benefit from stable housing, established schools, and neighborhood consistency.
- Ideal For: Families planning to stay 7+ years, those seeking stability, entrepreneurs building local businesses, and people who enjoy home improvement projects.
North Texas Lifestyle Considerations
North Texas communities offer distinct characteristics. Plano and Frisco attract corporate professionals with excellent schools and modern amenities. McKinney and Allen appeal to families seeking suburban charm. Dallas offers urban living with diverse neighborhoods. Prosper provides small-town character with growing development.
Consider which community aligns with your lifestyle, then evaluate whether renting or buying makes sense within that context.
Conclusion: Making Your Informed Decision With Local Market Insights
The rent versus buy decision isn't one-size-fits-all. Instead, evaluate your situation across multiple dimensions:
Choose Renting If:
- You plan to relocate within 5 years
- You prefer predictable monthly costs
- You want minimal maintenance responsibility
- You're building an emergency fund or paying down debt
- You value flexibility and lifestyle simplicity
Choose Buying If:
- You plan to stay 7+ years in North Texas
- You have a stable income and solid credit
- You can afford a 10-20% down payment
- You want to build long-term wealth through equity
- You desire stability, control, and community roots
Final Thoughts
North Texas continues to grow and evolve, offering excellent opportunities for both renters and buyers. The key is understanding your financial capacity, lifestyle preferences, and long-term goals. Consult with a financial advisor and local real estate professional who understands the McKinney, Plano, Dallas, Allen, Frisco, and Prosper markets. They can provide personalized guidance based on current market conditions and your unique circumstances.
Whether you choose to rent or buy, make the decision intentionally—not by default. Your housing choice significantly impacts your financial future and quality of life, so invest time in making the right choice for you.