Beyond the Mortgage Payment
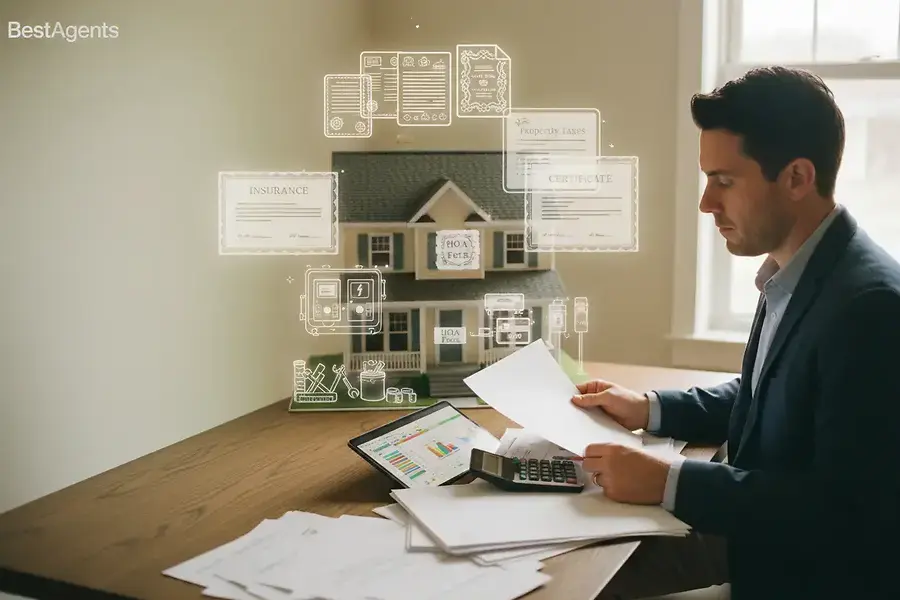
When most people think about homeownership costs, they focus on their monthly mortgage payment. However, this perspective significantly underestimates the true financial burden of owning a residential property. The reality is that your mortgage represents only a portion of your total housing expenses. Understanding and budgeting for these hidden costs is essential for making an informed decision about homeownership and avoiding financial surprises down the road.
Many first-time homebuyers are shocked to discover that their actual monthly housing expenses can be 30-50% higher than their mortgage payment alone. This gap exists because property ownership comes with numerous additional financial obligations that extend far beyond the principal and interest you pay to your lender. By the end of this guide, you'll have a comprehensive understanding of every cost category and how to calculate your true homeownership expenses.
Understanding Property Taxes, Assessments, and Local Levies
The Foundation of Property Tax Calculations
Property taxes represent one of the largest hidden costs of homeownership, yet many buyers don't fully understand how they're calculated. Property taxes are typically assessed as a percentage of your home's assessed value, which may differ from its market value. Local governments use these taxes to fund schools, infrastructure, emergency services, and other community services.
The amount you'll pay depends on several factors:
- Assessed Value: The value assigned to your property by the local assessor's office, which may be lower than your purchase price
- Tax Rate: The millage rate set by your local government, expressed as a percentage of assessed value
- Location: Property taxes vary dramatically by state and county, ranging from less than 0.5% to over 2% of home value annually
- Property Type: Residential, commercial, and agricultural properties often have different tax rates
Special Assessments and Local Levies
Beyond standard property taxes, homeowners may face special assessments for local improvements. These one-time or recurring charges fund specific projects like street repairs, water system upgrades, or new school construction. While not every homeowner will face special assessments, it's wise to research your local government's plans before purchasing.
Additionally, some communities impose local levies for specific services. These might include fire protection districts, library systems, or park maintenance. Understanding your complete tax burden requires investigating all these potential charges with your local tax assessor's office.
Insurance, HOA Fees, Maintenance, and Utility Budgeting
Homeowners Insurance: A Non-Negotiable Expense
If you have a mortgage, your lender requires homeowners insurance. This essential protection covers damage to your home's structure and contents from covered perils like fire, theft, and weather damage. Insurance costs vary based on your home's age, location, construction type, and coverage limits.
Key insurance considerations:
- Standard homeowners policies don't cover flood damage—you'll need separate flood insurance in high-risk areas
- Earthquake insurance is a separate policy in seismically active regions
- Your insurance costs may increase annually, so budget for potential rate hikes
- Shopping around every few years can help you find better rates
HOA Fees and Community Assessments
If you purchase a property in a homeowners association, you'll pay monthly or annual HOA fees. These fees fund community amenities, maintenance, insurance, and management. While HOA fees can range from $100 to over $500 monthly, they're often overlooked during the home-buying process.
Before purchasing in an HOA community, review the association's financial statements, reserve fund status, and any planned special assessments. A poorly managed HOA with insufficient reserves may impose surprise assessments on homeowners.
Maintenance and Repair Budgeting
One of the most unpredictable homeownership costs is maintenance and repairs. Unlike renters, homeowners are responsible for all structural and system repairs. Financial experts recommend budgeting 1-2% of your home's value annually for maintenance and unexpected repairs.
Common maintenance expenses include:
- HVAC system servicing and eventual replacement
- Roof repairs and replacement
- Plumbing and electrical repairs
- Appliance repairs and replacements
- Exterior maintenance like painting and landscaping
- Water heater replacement
Establishing a dedicated home maintenance fund helps you handle these expenses without financial stress. Many homeowners find that older homes require significantly higher maintenance budgets than newer properties.
Utilities and Essential Services
Your utility costs will depend on your home's size, age, climate, and energy efficiency. Budget for electricity, natural gas, water, sewer, and trash removal. In some areas, you may also pay for internet, security systems, and lawn care services.
Energy-efficient upgrades like insulation improvements, modern HVAC systems, and LED lighting can reduce utility costs over time. When evaluating a property, ask the seller for historical utility bills to estimate your actual expenses.
Making an Informed Homeownership Decision
Understanding the complete financial picture of homeownership is crucial before making this significant investment. To calculate your true monthly housing costs, add together your mortgage payment, property taxes, homeowners insurance, HOA fees (if applicable), estimated maintenance reserves, and average utilities.
Many financial advisors suggest that your total housing costs shouldn't exceed 28-30% of your gross monthly income. This guideline helps ensure that homeownership remains affordable and doesn't strain your overall finances.
Before purchasing a home, take these steps:
- Research property tax rates and trends in your target area
- Obtain homeowners insurance quotes for the specific property
- Review HOA documents and financial statements thoroughly
- Have a professional home inspection to identify potential maintenance issues
- Request utility bills from the current owner
- Calculate your complete monthly housing budget
- Ensure this budget aligns with your financial goals and income
Homeownership can be a rewarding investment and a path to building wealth, but only when you enter into it with realistic expectations about costs. By understanding property taxes, insurance, maintenance, and other hidden expenses, you can make a confident decision about whether homeownership is right for you and ensure that your dream home doesn't become a financial nightmare.