Introduction: Why Closing Costs Matter More Than You Think
When you're excited about purchasing your dream home, it's easy to focus solely on the down payment and monthly mortgage. However, closing costs represent a significant expense that many first-time homebuyers overlook. These fees typically range from 2% to 5% of your home's purchase price, meaning on a $300,000 home, you could be looking at $6,000 to $15,000 in additional expenses.
Understanding closing costs isn't just about knowing the numbers—it's about taking control of your financial future. By familiarizing yourself with each fee and expense, you can budget more accurately, identify potential savings opportunities, and avoid unpleasant surprises on closing day. Let's explore what these costs entail and how you can navigate them strategically.
Breaking Down the Main Categories of Closing Costs
Loan-Related Fees
Your lender will charge several fees to process and fund your mortgage. These typically include:
- Origination Fee: Usually 0.5% to 1% of the loan amount, this covers the lender's administrative costs
- Appraisal Fee: Typically $300-$500, required to verify the home's value
- Credit Report Fee: Usually $25-$75 to pull your credit history
- Title Search and Insurance: Ranges from $200-$400, protecting you against ownership disputes
- Underwriting Fee: Typically $400-$900 for loan approval processing
These fees ensure your lender has properly vetted the property and your financial situation. While they're standard, some lenders may be willing to negotiate or waive certain fees, especially if you have excellent credit or a substantial down payment.
Government and Recording Fees
Local governments charge fees to record your deed and mortgage documents. These costs vary significantly by location but typically include:
- Recording fees for the deed and mortgage
- Transfer taxes (not applicable in all states)
- Property tax adjustments and prorations
- Homeowners association fees (if applicable)
Pro tip: Research your specific state and county requirements early in the process. Some areas have significantly higher transfer taxes than others, which could impact your total closing costs substantially.
Title and Insurance Costs
Title insurance protects you and your lender from future ownership claims. This typically includes:
- Owner's Title Insurance: One-time premium protecting your ownership rights
- Lender's Title Insurance: Protects the lender's investment in the property
- Title Search: Ensures no liens or claims exist against the property
While these costs are non-negotiable in most cases, you can shop around for the best title insurance rates, as prices vary between providers.
Professional Services and Inspections
Before closing, you'll need professional evaluations of the property:
- Home Inspection: $300-$500 for a thorough property evaluation
- Pest Inspection: $75-$150 to check for termites and other pests
- Survey: $200-$500 if required by your lender or local regulations
- Attorney Fees: $500-$1,500 in states requiring legal representation
These inspections protect your investment and identify potential issues before you commit to the purchase.
Prepaid Items and Escrow
Your lender may require you to prepay certain expenses at closing:
- Property Taxes: Prorated amount for the remainder of the year
- Homeowners Insurance: First year premium or initial payment
- HOA Fees: Prepaid amounts if applicable
- Escrow Deposits: Funds held for future tax and insurance payments
These aren't additional costs per se—they're expenses you'd pay anyway, just collected upfront at closing.
Negotiating and Reducing Your Closing Expenses
Shop Around for Services
Don't accept the first quote you receive. Lenders are required to provide a Loan Estimate within three days of application, allowing you to compare rates and fees across multiple lenders. Similarly, get quotes from different title companies, appraisers, and inspectors. Even small savings on each service add up significantly.
Request Lender Credits
Many lenders offer credits or discounts to competitive borrowers. If you have strong credit, a substantial down payment, or are bringing significant assets to the lender, negotiate for:
- Reduced origination fees
- Waived underwriting fees
- Lender credits toward closing costs
Negotiate with the Seller
In many real estate transactions, sellers contribute to buyer closing costs. This is especially common in competitive markets or when you're making a strong offer. Request seller concessions for closing costs as part of your purchase agreement negotiations.
Avoid Unnecessary Services
Review your Loan Estimate carefully. Some lenders bundle services you may not need or can obtain elsewhere more cheaply. Question every fee and ask your lender to explain what each one covers. Don't hesitate to request removal of unnecessary charges.
Lock in Your Rate Early
Rate lock agreements can prevent your interest rate from increasing before closing, which protects you from additional costs if rates rise. However, be aware that locking in too early might result in fees if you need to extend the lock period.
Conclusion: Preparing Financially for Your Home Purchase
Closing costs are a reality of home purchasing, but they don't have to catch you off guard. By understanding the various categories of fees, shopping around for services, and actively negotiating, you can significantly reduce your total expenses.
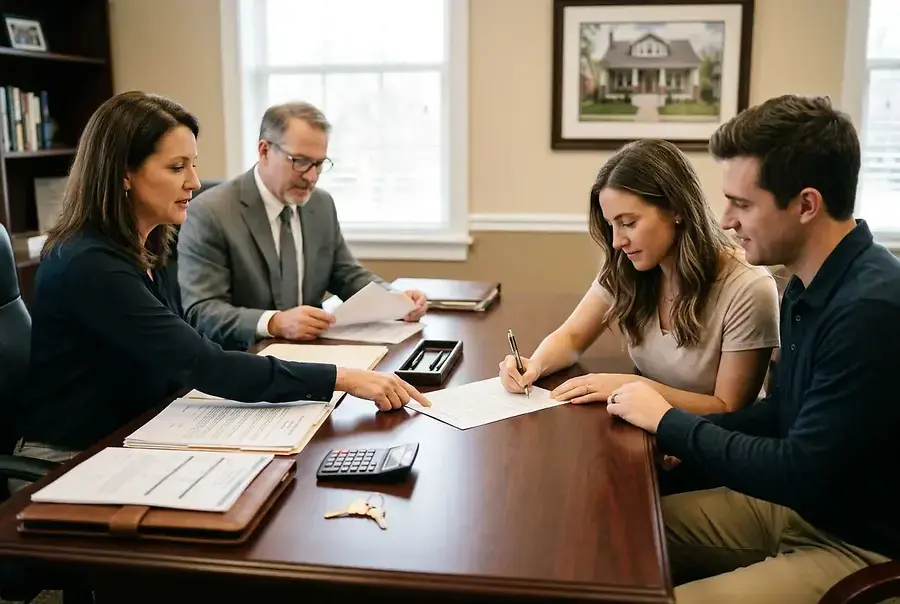
Remember: Knowledge is power in real estate transactions. The time you invest in understanding closing costs now will pay dividends when you sit down at the closing table.
Start by requesting a detailed Loan Estimate from multiple lenders, comparing not just interest rates but all associated fees. Ask questions about anything you don't understand, and don't be afraid to negotiate. Many homebuyers successfully reduce their closing costs by 10-20% through informed shopping and negotiation.
Your home purchase is likely the largest financial transaction of your life. By taking control of your closing costs, you're not just saving money—you're taking an active role in protecting your financial future. Approach closing day with confidence, knowing you've done your due diligence and secured the best possible terms for your new home.