Understanding Home Appraisals: What Lenders Look For
A home appraisal is an independent assessment of a property's market value, conducted by a licensed professional appraiser. When you apply for a mortgage, your lender requires an appraisal to ensure the property is worth the amount you're borrowing. This protects both you and the lender from overpaying for a home.
The Appraisal Process
Appraisers evaluate several key factors when determining a home's value:
- Comparable Sales: Recent sales of similar properties in your neighborhood
- Property Condition: The home's structural integrity, age, and overall maintenance
- Location and Neighborhood: School districts, crime rates, and local amenities
- Square Footage and Layout: The home's size, number of rooms, and functional design
- Upgrades and Features: Modern appliances, renovations, and special amenities
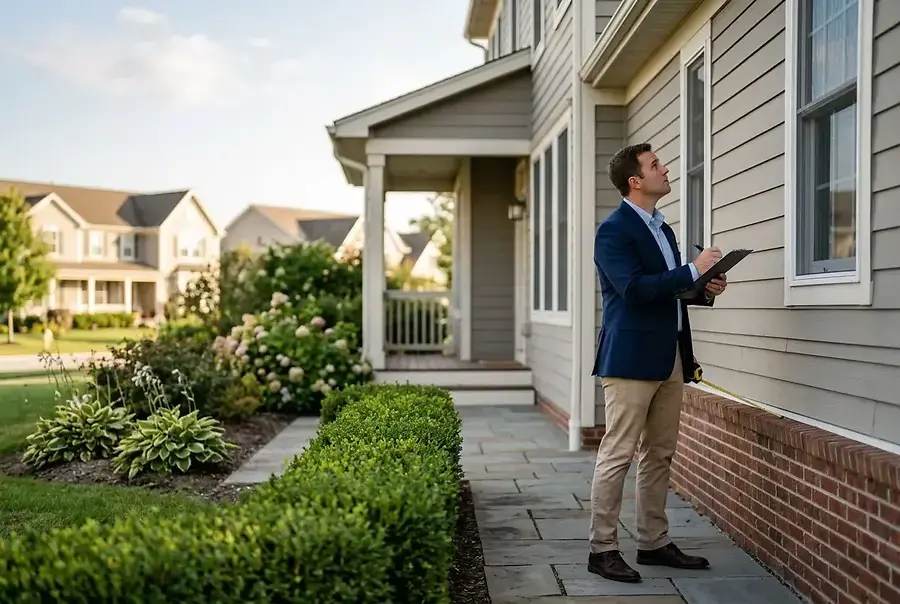
The appraiser will conduct a thorough inspection, take measurements, and review public records to compile their report. This typically takes one to two weeks from the time the appraisal is ordered.
Why Appraisals Matter
Lenders use appraisals to determine the loan-to-value ratio (LTV), which affects your mortgage terms, interest rates, and whether you'll need private mortgage insurance (PMI). A higher appraisal strengthens your position, while a lower one can create complications.
How Low Appraisals Impact Your Financing and Deal Timeline
When a home appraises for less than the agreed purchase price, you face a challenging situation that requires immediate attention and strategic thinking.
The Financial Consequences
If you agreed to purchase a home for $350,000 but it appraises for $330,000, you have a $20,000 gap. Your lender will only finance based on the appraised value, meaning you must either:
- Cover the difference out of pocket
- Renegotiate the purchase price with the seller
- Request the seller contribute to closing costs
- Walk away from the deal (if your contract allows)
This gap directly impacts your down payment percentage and monthly mortgage payments. A lower appraisal increases your LTV ratio, potentially triggering PMI requirements or higher interest rates.
Timeline Delays
A low appraisal can derail your closing timeline. You'll need time to negotiate with the seller, gather additional documentation, or request a second appraisal. These delays can extend your closing date by weeks, affecting your moving plans and potentially creating complications with your current housing situation.
Emotional and Psychological Impact
A low appraisal can feel like a personal rejection of your dream home, but remember—it's a professional assessment of market value, not a judgment on the property's worth to you.
Many buyers feel disappointed or frustrated when facing an appraisal gap. It's important to separate emotions from the financial reality and focus on practical solutions.
Strategies for Addressing Appraisal Gaps and Renegotiating Terms
Request an Appraisal Review
Before accepting a low appraisal, ask your real estate agent to review the appraiser's report for errors. Common mistakes include incorrect square footage, missing upgrades, or inaccurate comparable sales. If you find errors, you can request a reconsideration of value from the appraiser.
Provide Additional Documentation
Submit evidence of recent renovations, upgrades, or improvements that the appraiser may have missed. Photos, receipts, and contractor invoices can support a higher valuation. If comparable sales data was incomplete, provide additional recent sales in your neighborhood.
Negotiate with the Seller
Armed with the appraisal report, approach the seller with a professional renegotiation request. Explain that the appraisal came in lower than expected and propose a new purchase price that reflects the appraised value. Many sellers will negotiate rather than lose the sale.
Split the Difference
If the seller won't accept a full price reduction, propose meeting halfway. For a $20,000 gap, you might ask the seller to reduce the price by $10,000 while you cover the remaining $10,000 out of pocket.
Request Seller Concessions
Instead of a price reduction, ask the seller to contribute to your closing costs or provide credits for repairs. This reduces your out-of-pocket expenses without changing the purchase price.
Order a Second Appraisal
If you believe the appraisal is significantly off, you can request a second appraisal at your own expense. However, this is costly and time-consuming, so use this option only when you have strong evidence the first appraisal was inaccurate.
Protecting Your Investment: Next Steps After Appraisal Results
If the Appraisal Comes in High
Congratulations! A high appraisal strengthens your negotiating position and may allow you to refinance at better terms in the future. It also means you're building equity immediately and have a stronger financial position in your purchase.
If the Appraisal Meets Expectations
You can proceed with confidence toward closing. The appraisal validates your purchase price and ensures you're not overpaying for the property.
If the Appraisal Comes in Low
Take action immediately. Don't wait passively—contact your real estate agent, review the report carefully, and begin negotiations within days. The longer you wait, the closer you get to your closing date, which limits your options.
Document Everything
Keep detailed records of all communications, appraisal reports, comparable sales data, and negotiation offers. This documentation protects you legally and provides evidence if disputes arise.
Consider Your Long-Term Position
Before walking away from a deal due to an appraisal gap, consider whether the home is still a good investment at the appraised value. Sometimes the market has simply corrected, and the appraised price is more accurate than your original offer.
Home appraisals are a critical component of the mortgage process that directly affects your financing, timeline, and negotiating power. By understanding how appraisals work and preparing strategies to address potential gaps, you can navigate this process confidently and protect your investment. Remember, an appraisal is a professional assessment designed to protect both you and your lender—use it as a tool to make informed decisions about one of the most important purchases of your life.