Introduction: Understanding the True Cost of Homeownership
Buying a home is often considered the American dream, but many first-time homeowners are shocked to discover that their mortgage payment represents only a fraction of their actual housing costs. While the monthly mortgage payment is the most visible expense, numerous other costs lurk beneath the surface, waiting to impact your budget. Understanding these hidden expenses is crucial for making informed financial decisions and avoiding unexpected hardships down the road.
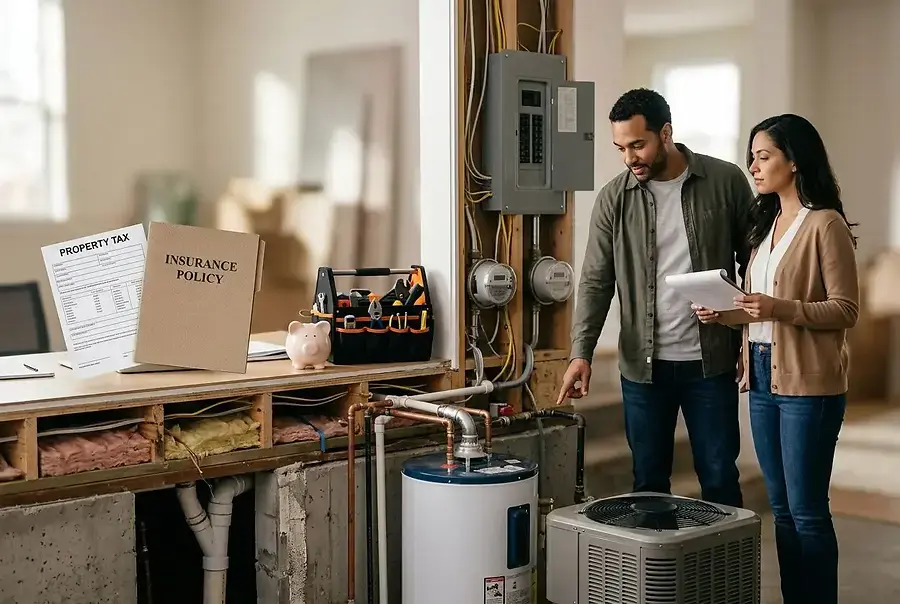
The true cost of homeownership extends far beyond the principal and interest you pay each month. Property taxes, insurance, maintenance, utilities, and various other fees can easily add 50% or more to your monthly housing expenses. By recognizing these costs upfront, you can create a realistic budget that accounts for all aspects of homeownership and ensures long-term financial stability.
Property Taxes, Insurance, and Maintenance: The Big Three Expenses
Property Taxes: A Continuous Obligation
Property taxes are one of the most significant ongoing costs of homeownership, yet many buyers underestimate their impact. These taxes vary dramatically depending on your location, with some areas charging substantially more than others. Property taxes typically range from 0.3% to 2.5% of your home's value annually, though this can vary widely by state and municipality.
What makes property taxes particularly important to understand is that they increase over time. As your home appreciates in value, your tax bill will likely increase as well. Additionally, local governments may raise tax rates, further increasing your burden. It's essential to research property tax rates in your area before purchasing and budget accordingly for potential increases.
Homeowners Insurance: Protecting Your Investment
Homeowners insurance is not optional—it's required by virtually every mortgage lender. This insurance protects your home and personal belongings from damage caused by fire, theft, weather, and other covered events. The average homeowners insurance policy costs between $1,000 and $2,000 annually, though this varies based on your home's age, location, and the coverage level you choose.
Beyond standard homeowners insurance, you may need additional coverage. If your home is in a flood-prone area, flood insurance is essential and must be purchased separately. Similarly, if you live in an earthquake-prone region, earthquake insurance may be necessary. These supplemental policies add to your annual expenses but provide critical protection against catastrophic losses.
Home Maintenance: The Often-Overlooked Expense
Home maintenance is perhaps the most unpredictable of the big three expenses, yet it's absolutely critical to budget for it. The general rule of thumb is to set aside 1% to 2% of your home's purchase price annually for maintenance and repairs. For a $300,000 home, this means budgeting $3,000 to $6,000 per year.
Maintenance costs include routine tasks like:
- HVAC system servicing and filter replacements
- Roof inspections and repairs
- Plumbing maintenance and repairs
- Painting and exterior maintenance
- Appliance repairs and replacements
Without proper maintenance, small issues can escalate into expensive problems. A neglected roof leak can lead to structural damage, and deferred HVAC maintenance can result in complete system failure during extreme weather.
Utilities, HOA Fees, and Unexpected Repairs: Planning for the Rest
Utilities: More Than Just Electricity and Water
Utility costs are often underestimated by new homeowners. Beyond electricity and water, you may need to budget for natural gas, internet, phone service, and trash collection. These costs vary significantly based on your climate, home size, and usage patterns. In colder climates, heating costs can be substantial, while air conditioning expenses dominate in warmer regions.
To get an accurate picture of utility costs, ask the previous homeowner or utility company for historical usage data. This will give you a realistic estimate of what to expect throughout the year, including seasonal variations.
HOA Fees: A Hidden Recurring Expense
If you purchase a home in a community with a homeowners association (HOA), you'll face monthly or annual HOA fees. These fees typically range from $100 to $500 monthly, depending on the community and amenities provided. While HOA fees cover community maintenance and amenities, they represent a significant ongoing expense that many buyers overlook.
Important considerations regarding HOA fees:
- Fees often increase annually
- Special assessments may be levied for major repairs or improvements
- The HOA may have restrictions on renovations and modifications
- Failure to pay HOA fees can result in liens against your property
Unexpected Repairs: The Budget Killer
Even with diligent maintenance, unexpected repairs will happen. A water heater failure, foundation crack, or electrical issue can cost thousands of dollars to repair. This is why financial experts recommend maintaining an emergency fund specifically for home repairs—ideally 3 to 6 months of your total housing expenses.
Common unexpected repairs include:
- Water heater replacement ($1,000-$3,000)
- Roof replacement ($5,000-$15,000)
- Foundation repairs ($2,000-$10,000+)
- Electrical system upgrades ($3,000-$8,000)
- Plumbing emergencies ($500-$5,000)
Conclusion: Creating a Realistic Budget for Long-Term Success
Successful homeownership requires understanding and planning for all associated costs, not just your mortgage payment. By accounting for property taxes, insurance, maintenance, utilities, HOA fees, and unexpected repairs, you can create a comprehensive budget that reflects the true cost of owning your home.
To ensure long-term financial success as a homeowner:
- Research all costs specific to your location and property before purchasing
- Set aside funds monthly for maintenance and repairs
- Maintain an emergency fund for unexpected expenses
- Review your budget annually and adjust for changes
- Consider working with a financial advisor to plan for homeownership costs
Homeownership can be incredibly rewarding, but it requires careful financial planning and realistic expectations. By understanding the hidden costs beyond your mortgage payment, you'll be better prepared to manage your finances, avoid surprises, and enjoy the benefits of owning your home for years to come.