Introduction: Understanding the Complete Picture of Homeownership Costs
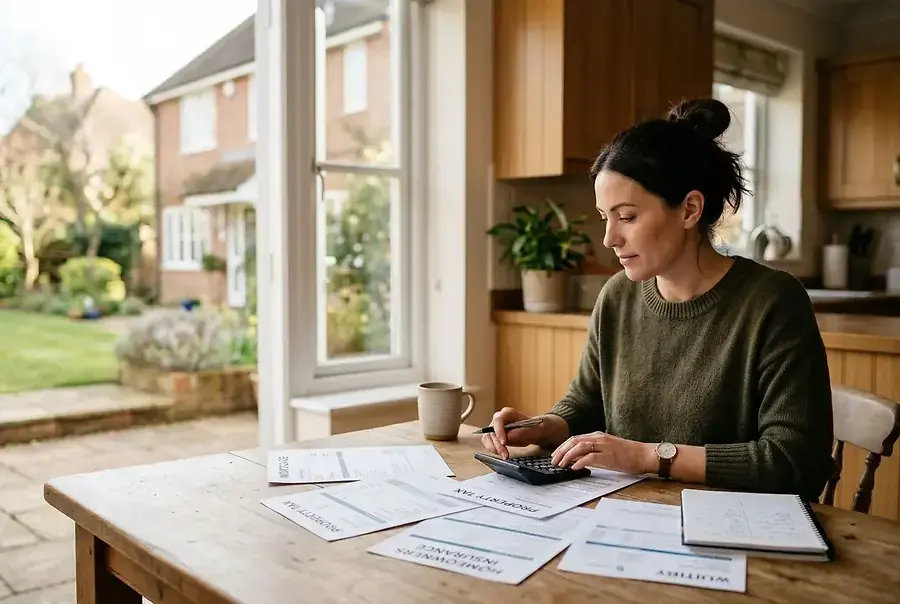
Buying a home is one of the most significant financial decisions you'll make in your lifetime. While many prospective homeowners focus primarily on their monthly mortgage payment, the true cost of homeownership extends far beyond this single expense. Understanding the complete financial picture is essential for making informed decisions and avoiding unexpected financial hardships down the road.
When you become a homeowner, you're not just paying for the privilege of living in a property—you're taking on a range of ongoing financial responsibilities. These hidden expenses can quickly add up, potentially increasing your housing costs by 25-50% beyond your mortgage payment. By recognizing and planning for these costs upfront, you can create a sustainable financial plan that allows you to enjoy your home without financial stress.
Beyond the Mortgage: Property Taxes, Insurance, and HOA Fees Explained
Property Taxes
One of the most significant ongoing expenses for homeowners is property taxes. These taxes are levied by local governments and are used to fund schools, infrastructure, and public services. Property tax rates vary dramatically depending on your location, ranging from less than 1% to over 2% of your home's assessed value annually.
Key points about property taxes:
- Taxes are typically paid annually or semi-annually
- Your assessed home value may increase over time, raising your tax burden
- Some states offer homestead exemptions that can reduce your tax liability
- Property taxes are often included in your mortgage payment through escrow accounts
Homeowners Insurance
Homeowners insurance is a non-negotiable expense that protects your investment against damage, theft, and liability. Most mortgage lenders require proof of insurance before closing on your home. The cost varies based on factors such as your home's age, location, construction materials, and the coverage level you choose.
Average homeowners insurance costs range from $800 to $2,000 annually, though this can be significantly higher in areas prone to natural disasters. Beyond standard coverage, you may need additional policies for flood insurance or earthquake coverage, depending on your geographic location.
HOA Fees
If you purchase a property in a community with a homeowners association, you'll be required to pay monthly or annual HOA fees. These fees fund community amenities, maintenance of common areas, and reserve funds for major repairs. HOA fees can range from $100 to several hundred dollars monthly, and they typically increase over time.
Remember: HOA fees are mandatory and non-negotiable if you live in a community with an HOA. Always review the HOA's financial statements and reserve fund before purchasing a property.
Maintenance and Repair Budgeting: Planning for the Unexpected
The 1% Rule
Financial experts recommend setting aside 1% of your home's purchase price annually for maintenance and repairs. For a $300,000 home, this translates to $3,000 per year or $250 monthly. This reserve fund helps you handle unexpected repairs without derailing your finances.
Common Maintenance Expenses
Regular maintenance is essential for preserving your home's value and preventing costly repairs. Budget for these common expenses:
- HVAC maintenance: Annual inspections and filter replacements ($150-$300)
- Roof inspections: Every 3-5 years ($200-$500)
- Plumbing: Drain cleaning and pipe maintenance ($100-$500)
- Exterior maintenance: Gutter cleaning, landscaping, and painting ($500-$2,000 annually)
- Appliance repairs: Unexpected breakdowns can cost $300-$1,500 per appliance
Major Repairs and Replacements
Beyond routine maintenance, homeowners must prepare for major expenses that occur less frequently but carry significant costs. A roof replacement can cost $5,000-$15,000, while a new water heater runs $1,000-$3,000. Foundation repairs, electrical system upgrades, and HVAC replacements are among the most expensive home repairs you might face.
Building an emergency fund specifically for home repairs is crucial. Aim to accumulate 3-6 months of housing expenses in a dedicated savings account to handle unexpected major repairs without resorting to credit cards or loans.
Utilities and Services
Don't overlook the cost of utilities, which can vary significantly based on climate, home size, and energy efficiency. Budget for electricity, gas, water, sewer, trash removal, and internet services. These costs typically range from $200-$400 monthly, depending on your location and usage patterns.
Conclusion: Creating a Realistic Financial Plan for Sustainable Homeownership
Successful homeownership requires a comprehensive understanding of all associated costs, not just your mortgage payment. By accounting for property taxes, insurance, HOA fees, maintenance, and utilities, you can create a realistic budget that ensures long-term financial stability.
Here's a practical approach to budgeting for homeownership:
- Calculate your total monthly housing costs, including mortgage, taxes, insurance, and utilities
- Set aside 1% of your home's value annually for maintenance and repairs
- Build an emergency fund for unexpected major repairs
- Review your budget annually and adjust as needed
- Consider energy-efficient upgrades to reduce utility costs over time
Homeownership is a rewarding investment that builds equity and provides stability. However, it requires careful financial planning and realistic expectations about ongoing costs. By understanding the true cost of homeownership and preparing accordingly, you can enjoy your home with confidence and financial peace of mind.
Take the time to thoroughly evaluate all expenses before purchasing a home, and don't hesitate to consult with financial advisors or experienced homeowners who can provide valuable insights based on their experiences. Your future self will thank you for the diligent planning you do today.