Introduction: The Critical Role of Home Appraisals in Real Estate Transactions
A home appraisal is one of the most important steps in any real estate transaction, yet many buyers and sellers don't fully understand what it entails or why it matters. Whether you're purchasing your first home, selling a property, or refinancing a mortgage, an appraisal can significantly impact your financial outcome. An appraisal is an independent, professional assessment of a property's market value, conducted by a licensed appraiser who evaluates the home based on comparable sales, property condition, and market trends.
Understanding how appraisals work can help you prepare for the process, anticipate potential issues, and make more informed decisions about your real estate investments. In this guide, we'll explore what happens during an appraisal, the factors that influence your home's valuation, and how you can use this knowledge to your advantage.
What Happens During a Home Appraisal and How Appraisers Determine Value
The Appraisal Process
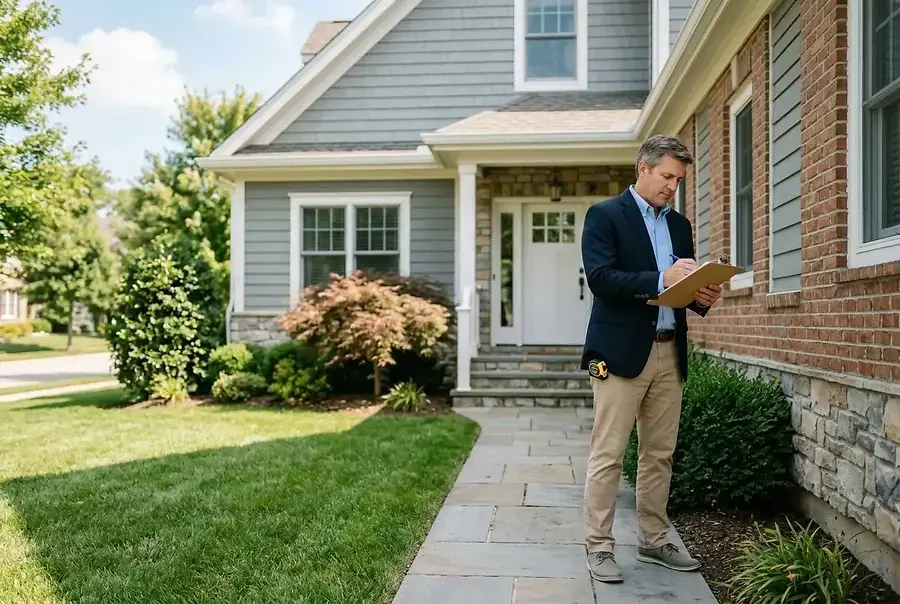
When a home appraisal is ordered—typically by a lender during the mortgage process—a certified appraiser is assigned to evaluate the property. The appraiser will schedule a visit to inspect the home thoroughly, examining both the interior and exterior. This inspection typically takes one to three hours, depending on the property's size and complexity.
During the inspection, the appraiser will:
- Measure the square footage of the home
- Assess the overall condition of the structure, roof, and foundation
- Evaluate the quality of construction and materials used
- Inspect major systems including plumbing, electrical, and HVAC
- Document the number of bedrooms, bathrooms, and living spaces
- Note any upgrades, renovations, or damage
- Evaluate the lot size and landscaping
Valuation Methods
Appraisers use several methods to determine a property's value, with the most common being the sales comparison approach. This method involves analyzing recent sales of comparable properties—homes similar in size, condition, location, and features—to establish a fair market value for the subject property. Appraisers adjust prices up or down based on differences between the comparable homes and the property being appraised.
For investment properties or unique homes, appraisers may also use the income approach (based on rental income potential) or the cost approach (based on replacement cost). However, the sales comparison approach remains the most widely used method for residential properties.
The Appraisal Report
After completing the inspection and analysis, the appraiser prepares a detailed report that includes photographs, measurements, descriptions of the property's condition, comparable sales data, and the final appraised value. This report is typically completed within 3-5 business days and is provided to the lender, who then shares it with the buyer and seller.
Common Factors That Impact Your Property's Appraised Value
Location and Market Conditions
Location is one of the most significant factors affecting property value. Homes in desirable neighborhoods with good schools, low crime rates, and convenient access to amenities typically appraise higher than similar homes in less desirable areas. Additionally, current market conditions—whether it's a buyer's market or seller's market—influence appraisal values. Recent comparable sales in your area directly impact how your home is valued.
Property Condition and Age
The overall condition of your home plays a crucial role in its appraised value. Well-maintained homes with updated systems and modern finishes typically appraise higher than homes requiring significant repairs. The age of the home also matters; newer homes or those with recent major renovations (roof, HVAC, plumbing) often command higher values. Conversely, deferred maintenance, structural issues, or outdated systems can negatively impact your appraisal.
Size and Layout
Square footage is a primary driver of home value. Appraisers carefully measure the livable space and compare it to similar properties. However, it's not just about size—the layout and functionality of the space matter too. Homes with efficient floor plans, desirable room configurations, and good flow typically appraise higher than homes with awkward layouts, even if they have similar square footage.
Upgrades and Improvements
Strategic renovations can positively impact your appraisal. Kitchen and bathroom upgrades, energy-efficient windows, updated flooring, and modern appliances often provide good returns. However, not all improvements add dollar-for-dollar value. Highly personalized upgrades or luxury features that exceed the neighborhood standard may not fully recoup their cost in the appraisal.
Lot Size and Outdoor Features
The size and quality of your lot influence property value. Larger lots in desirable locations command premium prices. Outdoor features such as:
- Well-maintained landscaping
- Decks, patios, or outdoor living spaces
- Swimming pools (which can be a plus or minus depending on the market)
- Mature trees and natural features
- Proximity to parks or water features
All contribute to the overall appeal and value of your property.
Comparable Sales Data
The appraisal heavily relies on recent sales of comparable properties in your area. Appraisers typically use 3-5 comparable sales from the past 3-6 months to establish fair market value. If comparable homes have sold at higher or lower prices recently, this directly influences your appraisal. In fast-moving markets, older comparable sales may not accurately reflect current values.
Conclusion: Using Appraisal Knowledge to Your Advantage in Real Estate
Understanding home appraisals empowers you to make better real estate decisions. For sellers, knowing what appraisers look for allows you to prepare your home strategically and set realistic asking prices. Focus on curb appeal, cleanliness, and addressing obvious maintenance issues before an appraisal. For buyers, understanding appraisals helps you recognize when a property may be overpriced and protects you from overpaying.
If your appraisal comes in lower than expected, you have options. You can request a reconsideration of value if you believe the appraisal is inaccurate, provide additional comparable sales data, or negotiate the purchase price with the seller. Similarly, if you're selling and the appraisal is higher than anticipated, you're in a strong negotiating position.
By understanding how appraisers determine value and what factors influence your property's appraisal, you'll be better equipped to navigate real estate transactions with confidence and achieve your financial goals.