Introduction: Why Property Taxes Matter for Kailua-Kona Buyers
Purchasing property in Kailua-Kona is a significant investment, and understanding the full financial picture is essential for making informed decisions. While many prospective buyers focus on purchase price and mortgage rates, property taxes represent an ongoing cost that directly impacts your long-term investment returns and annual expenses. Property taxes in Hawaii are notably lower than on the mainland, but they still deserve careful consideration when budgeting for your new home.
Whether you're a first-time homebuyer or an experienced investor, comprehending how Hawaii's property tax system works will help you avoid surprises and plan your finances more effectively. This guide walks you through the essentials of property taxation in Kailua-Kona and surrounding residential communities.
How Hawaii's Property Tax System Works for Residential Properties
The Basics of Hawaii Property Taxation
Hawaii operates a unique property tax system that differs significantly from mainland states. The state assesses property taxes at the county level, meaning rates and assessment methods can vary between Hawaii County, Maui County, Honolulu County, and Kalawao County. For Kailua-Kona properties, you'll be dealing with Hawaii County's tax structure.
The property tax calculation in Hawaii follows this formula:
Property Tax = Assessed Value × Tax Rate
Assessment and Valuation Process
Hawaii County assesses residential properties based on their fair market value. The assessment process involves:
- Professional appraisals conducted by county assessors
- Comparison with recent sales of similar properties in your area
- Consideration of property features, location, and condition
- Regular reassessments to ensure current market values
Property owners receive assessment notices and have the right to appeal if they believe their assessment is inaccurate. It's wise to review your assessment carefully and compare it with similar properties in your neighborhood.
Tax Rates and Exemptions
Hawaii County applies different tax rates based on property classification. Residential properties typically enjoy lower tax rates compared to commercial or agricultural properties. The state also offers several exemptions and deferrals that may apply to your situation:
- Homeowner's Exemption: Reduces the assessed value for owner-occupied homes
- Disability Exemption: Available for disabled homeowners
- Senior Citizen Exemption: Provides relief for qualifying seniors
- Tax Deferral Program: Allows eligible homeowners to defer taxes under certain conditions
Determining your eligibility for these programs can result in substantial savings, so it's worth investigating whether you qualify.
Tax Implications Specific to Kailua-Kona, Keauhou, and Waikoloa
Kailua-Kona Residential Market Characteristics
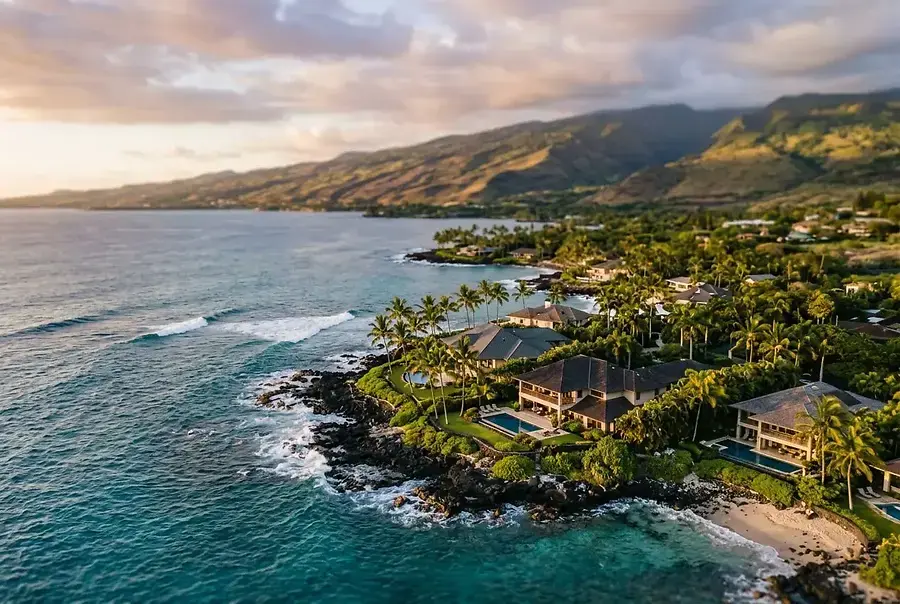
Kailua-Kona is one of Hawaii's most desirable residential communities, known for its stunning oceanfront views, excellent weather, and vibrant community atmosphere. Property values in Kailua-Kona tend to be higher than in many other Big Island communities, which directly affects your property tax obligations.
The assessed values in Kailua-Kona reflect the premium location and amenities. A typical oceanfront or oceanview property will have a significantly higher assessed value than a comparable property in a less desirable area. This means your annual property tax bill will be proportionally higher, but you're also investing in one of Hawaii's most sought-after locations.
Keauhou and Waikoloa Considerations
Keauhou, located just south of Kailua-Kona, offers slightly more affordable property values while maintaining excellent quality of life. Properties in Keauhou may have lower assessed values than comparable Kailua-Kona properties, resulting in reduced tax obligations. However, the difference in property taxes should be weighed against other factors such as location, amenities, and long-term appreciation potential.
Waikoloa, situated on the Kohala Coast, represents another premium residential option. This master-planned community features resort-style amenities and championship golf courses. Properties here command premium prices and assessments, reflecting the exclusive nature of the community.
Factors Affecting Your Tax Bill
Several specific factors influence property tax amounts in these communities:
- Ocean proximity: Oceanfront and oceanview properties command higher assessments
- Land size: Larger parcels typically result in higher tax obligations
- Improvements: Home upgrades and renovations may trigger reassessment
- Community amenities: Access to golf courses, pools, and security features affects value
- Market trends: Rising property values in the area increase assessments over time
Understanding these factors helps you anticipate potential changes to your tax bill and plan accordingly.
Planning for Tax Increases
Property taxes are not static—they can increase as property values rise and as you make improvements to your home. When budgeting for your Kailua-Kona property, factor in potential annual increases. Hawaii County typically reassesses properties periodically, and significant home improvements may trigger immediate reassessment.
Keeping detailed records of your property's condition and any improvements you make can help you understand and potentially challenge assessments if they seem excessive.
Conclusion: Making Informed Investment Decisions
Property taxes are a crucial component of homeownership costs in Kailua-Kona and surrounding communities. While Hawaii's property tax rates are generally favorable compared to mainland states, the premium property values in these desirable locations mean your annual tax obligations will be significant.
To make the most informed decision when purchasing property in Kailua-Kona, Keauhou, or Waikoloa:
- Request property tax information for any property you're considering
- Factor annual property taxes into your total cost of ownership calculations
- Investigate available exemptions and deferrals for which you may qualify
- Review assessment notices carefully and appeal if you believe they're inaccurate
- Work with a local real estate professional familiar with Big Island tax implications
- Plan for potential tax increases as property values appreciate
By understanding Hawaii's property tax system and how it applies specifically to your chosen community, you'll be better equipped to make a sound investment decision. Property ownership in Kailua-Kona offers tremendous lifestyle and investment benefits, and with proper financial planning that includes realistic property tax expectations, you can enjoy your Hawaiian home with confidence and peace of mind.