What Home Appraisals Are and Why Lenders Require Them
A home appraisal is an independent, professional assessment of a property's market value. When you're purchasing a home in Racine, your lender requires an appraisal to ensure the property is worth the amount you're borrowing. This protects both you and the financial institution from overpaying for a property.
Lenders require appraisals because they use the home as collateral for your mortgage. If you default on your loan, the lender needs to know they can recover their investment by selling the property. An appraisal provides an objective valuation that justifies the loan amount, making it a critical step in the mortgage approval process.
Key reasons lenders require appraisals:
- To verify the property value matches the purchase price
- To protect their financial investment
- To ensure compliance with lending regulations
- To determine appropriate loan-to-value ratios
How Appraisals Work: The Process and Timeline in Racine
The Appraisal Process
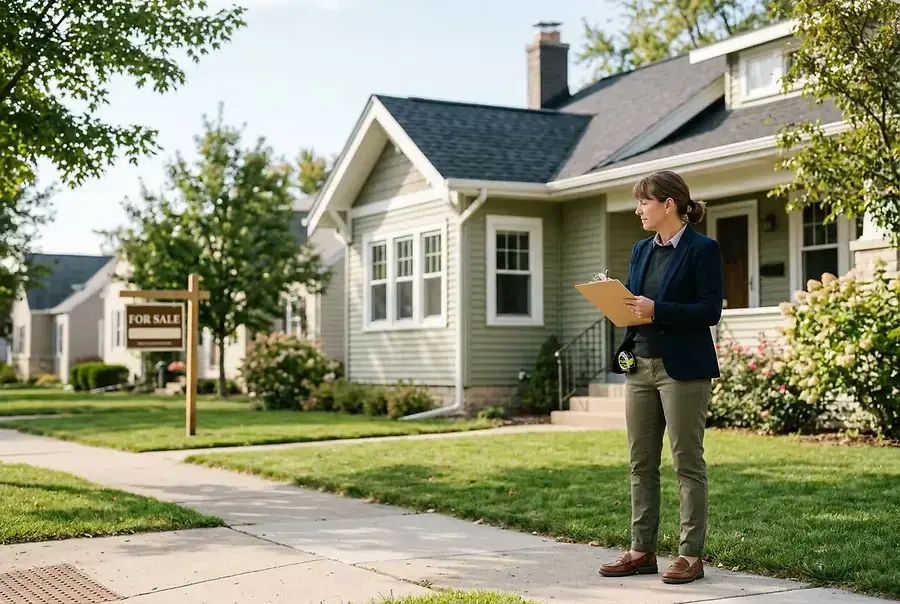
Once your offer is accepted, your lender orders an appraisal from a licensed appraiser. In Racine, appraisers are familiar with local market conditions, neighborhood trends, and comparable properties. The appraiser will conduct a thorough inspection of your property, examining everything from the foundation and roof to the interior condition and square footage.
The appraiser also researches comparable sales—recently sold homes in your area with similar characteristics. They analyze factors such as location, size, age, condition, and amenities to determine a fair market value for your property.
Timeline Expectations
In the Racine market, the appraisal process typically takes 7 to 10 business days from the time the lender orders it. However, this timeline can vary based on:
- The appraiser's current workload
- Property complexity and accessibility
- Market conditions in your specific neighborhood
- The need for additional research or inspections
Understanding this timeline helps you plan your closing date and manage expectations throughout the purchase process.
Common Appraisal Issues and How to Address Them
Low Appraisals
One of the most common issues homebuyers face is a low appraisal—when the appraised value comes in below the purchase price. This creates a gap between what you agreed to pay and what the property is actually worth according to the appraisal.
What you can do:
- Request a reconsideration: Ask your lender if the appraiser made any errors in their assessment. You can provide additional information about recent improvements or comparable sales the appraiser may have missed.
- Negotiate with the seller: The seller may agree to lower the price to match the appraisal value, especially in a balanced market.
- Increase your down payment: You can cover the difference yourself, though this requires additional capital.
- Walk away: If the gap is too large, you have the right to withdraw from the purchase without penalty.
Appraisal Contingencies
Most purchase agreements in Racine include an appraisal contingency, which protects you if the home appraises for less than the agreed purchase price. This clause gives you options and negotiating power, making it an essential component of your offer.
Factors That Affect Appraisal Values
Several factors can influence how an appraiser values your Racine property:
- Location and neighborhood desirability
- Property condition and age
- Recent renovations or upgrades
- Square footage and lot size
- Number of bedrooms and bathrooms
- Comparable sales in the area
- Market trends and economic conditions
Protecting Your Investment: Next Steps After Your Appraisal
Review the Appraisal Report
Once you receive the appraisal report, review it carefully. Check for any errors in property details, such as square footage, number of rooms, or condition assessments. If you notice inaccuracies, contact your real estate agent or lender immediately to request corrections.
Understand Your Options
If the appraisal comes in as expected, you're on track to close. However, if there are issues, understand all your options before making decisions. Consult with your real estate agent and lender to determine the best course of action for your situation.
Plan for the Future
The appraisal value becomes your home's official value for mortgage purposes. This affects your loan-to-value ratio, which may impact your interest rate and monthly payments. Keep the appraisal report for your records—you may need it for refinancing, insurance, or property tax assessments in the future.
Work with Local Experts
In the Racine market, working with experienced real estate professionals who understand local appraisal trends can be invaluable. They can help you prepare your home for appraisal, provide comparable sales data, and guide you through any appraisal-related challenges.
Remember: An appraisal is not an inspection. It's a valuation tool designed to protect lenders and ensure fair market pricing. Understanding this distinction helps you navigate the appraisal process with confidence.
Final Thoughts
Home appraisals are a standard and necessary part of the mortgage process in Racine. By understanding how they work, what affects them, and how to address potential issues, you can protect your investment and make informed decisions throughout your home purchase journey. Stay informed, ask questions, and work with trusted professionals to ensure a smooth appraisal process.