Introduction: Why Property Appraisals Matter for Buyers and Sellers
A residential property appraisal is one of the most critical components of any real estate transaction. Whether you're buying your dream home or selling a property you've cherished for years, understanding how appraisals work can significantly impact your financial outcome. An appraisal is an unbiased, professional assessment of your home's market value, conducted by a licensed appraiser who evaluates the property based on established standards and comparable sales in your area.
For buyers, an appraisal protects your investment by ensuring you're not overpaying for a property. For sellers, it helps establish a realistic asking price and can prevent deals from falling through due to valuation disputes. Lenders also rely heavily on appraisals to determine how much they're willing to finance, making this assessment essential for securing a mortgage.
Key Factors Appraisers Evaluate in Residential Properties
Structural Condition and Age
One of the first things an appraiser examines is the overall structural integrity of your home. This includes the foundation, roof, walls, and framing. The age of the property plays a significant role in valuation, as newer homes typically command higher prices. However, well-maintained older homes can retain excellent value if they've been properly updated and cared for.
Location and Neighborhood Characteristics
The old real estate adage "location, location, location" holds true in appraisals. Appraisers assess the neighborhood's desirability, proximity to schools, shopping centers, and employment hubs. They also consider factors such as:
- Crime rates and neighborhood safety
- Quality of local schools
- Proximity to public transportation
- Environmental factors and natural hazards
- Future development plans in the area
Interior Features and Condition
Appraisers conduct a thorough inspection of your home's interior, evaluating the condition of flooring, walls, ceilings, and paint. They assess the functionality of systems including electrical, plumbing, and HVAC units. The kitchen and bathrooms receive particular attention, as these rooms significantly influence a home's value. Modern appliances, updated fixtures, and quality finishes can boost your appraisal value considerably.
Square Footage and Layout
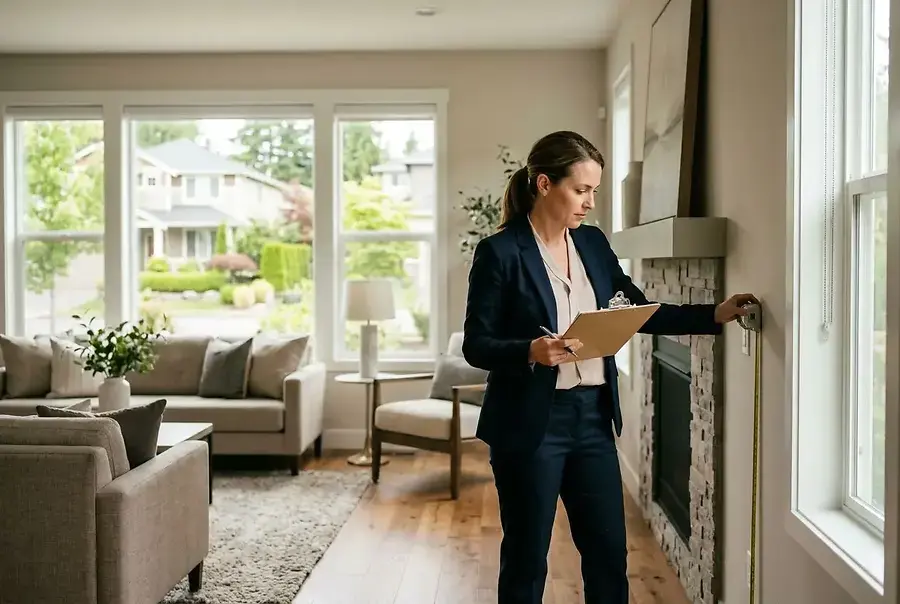
The total livable square footage is a fundamental metric in property appraisals. Appraisers measure the home's dimensions and calculate usable living space. They also evaluate the layout's functionality—whether the floor plan is efficient and appealing to potential buyers. Open-concept designs and well-organized spaces typically receive favorable assessments.
Comparable Sales Analysis
Appraisers don't work in isolation; they research comparable properties (or "comps") that have recently sold in your area. These similar homes serve as benchmarks for determining your property's fair market value. Factors considered when selecting comps include:
- Similar size and age
- Same neighborhood or nearby areas
- Recent sales within the last three to six months
- Similar condition and amenities
Special Features and Upgrades
Unique features can significantly enhance your home's appraised value. These might include a swimming pool, updated kitchen with premium appliances, energy-efficient windows, a finished basement, or a newly renovated bathroom. However, not all upgrades add dollar-for-dollar value, so it's important to make improvements that align with your neighborhood's standards.
How Appraisal Results Affect Your Real Estate Transaction
Impact on Mortgage Approval
When you apply for a mortgage, the lender orders an appraisal to ensure the property's value supports the loan amount. If the appraisal comes in lower than the agreed purchase price, you face several options: renegotiate the price, increase your down payment, or walk away from the deal. This is why appraisals are crucial—they protect both you and the lender from financing an overvalued property.
Determining Your Home's Market Value
An appraisal provides an objective assessment of what your home is worth in the current market. This information is invaluable for sellers setting asking prices and for homeowners understanding their property's equity. If you're refinancing, a higher appraisal can improve your loan-to-value ratio and potentially secure better interest rates.
Negotiation Leverage
If an appraisal reveals that a property is worth less than the purchase price, buyers can use this information to renegotiate. Conversely, if an appraisal exceeds expectations, sellers gain confidence in their asking price. Understanding appraisal results empowers both parties to make informed decisions during negotiations.
Property Tax Assessments
While different from appraisals, property tax assessments sometimes reference appraisal data. A higher appraised value could potentially affect your property taxes, so it's worth understanding how your local jurisdiction uses appraisal information.
Conclusion: Using Appraisal Knowledge to Make Informed Decisions
Understanding residential property appraisals is essential for anyone involved in real estate transactions. By knowing what appraisers evaluate and how their findings impact your deal, you can approach buying or selling with confidence and clarity. Whether you're a first-time homebuyer concerned about overpaying or a seller wanting to maximize your property's value, appraisal knowledge is your greatest asset.
Before your appraisal, ensure your home is clean and well-maintained, document any recent improvements, and provide the appraiser with information about upgrades or special features. If you disagree with an appraisal result, you have the right to request a review or obtain a second opinion. Remember, an appraisal is not just a number—it's a professional assessment that protects your financial interests and helps ensure fair market transactions for everyone involved.