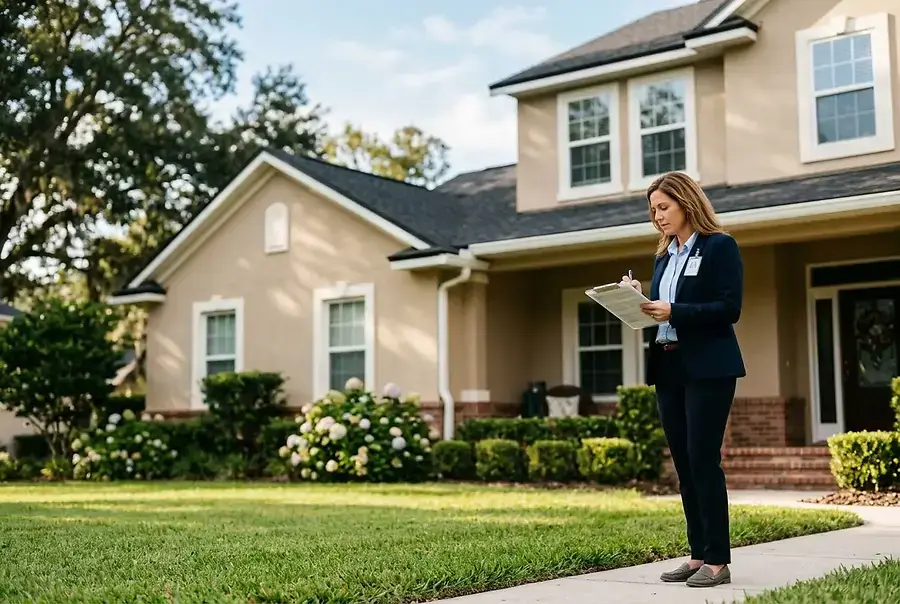
What Determines Your Home's Appraised Value
A residential property appraisal is a professional assessment of your home's fair market value. This valuation is crucial for mortgage lenders, buyers, and sellers alike. Several key factors influence how an appraiser determines your home's worth.
Location and Market Conditions
The location of your property is one of the most significant factors affecting its value. Homes in desirable neighborhoods with good schools, low crime rates, and convenient access to amenities typically command higher prices. Additionally, current market conditions—whether it's a buyer's or seller's market—play an important role in determining appraised values.
Property Characteristics
Appraisers carefully evaluate the physical characteristics of your home, including:
- Square footage and lot size – Larger homes and properties generally have higher values
- Age and condition – Newer homes or well-maintained properties typically appraise higher
- Number of bedrooms and bathrooms – More living spaces increase property value
- Structural integrity – Foundation, roof, and structural soundness are critical
- Upgrades and improvements – Modern kitchens, updated electrical systems, and quality finishes add value
Comparable Sales
Appraisers analyze recent sales of similar properties in your area, known as comparables or comps. These comparable sales provide a benchmark for determining your home's fair market value. Properties with similar features, size, and location that sold recently are particularly valuable for this analysis.
Common Appraisal Methods Used by Professionals
Professional appraisers use several standardized approaches to determine property values. Understanding these methods can help you appreciate the appraisal process.
The Sales Comparison Approach
This is the most commonly used method for residential properties. Appraisers compare your home to recently sold properties with similar characteristics. They adjust for differences in features, condition, and location to arrive at an estimated value. This method is particularly reliable in active real estate markets where comparable sales data is readily available.
The Cost Approach
The cost approach calculates the value by estimating the cost to rebuild your home from scratch, then subtracting depreciation and adding the land value. This method is useful for newer homes or properties with unique features that don't have many comparable sales. It's less commonly used as the primary valuation method but serves as a useful verification tool.
The Income Approach
While primarily used for investment properties, the income approach may be applied to residential properties that generate rental income. This method values the property based on the income it produces. Appraisers calculate the potential rental income and apply a capitalization rate to determine value.
How to Prepare for a Residential Property Appraisal
Proper preparation can help ensure your home is appraised fairly. Here are essential steps to take before the appraiser arrives.
Enhance Your Home's Curb Appeal
First impressions matter. Ensure your property's exterior is well-maintained:
- Trim landscaping and maintain the lawn
- Clean or repair the exterior siding
- Ensure the roof appears to be in good condition
- Paint the front door and maintain the entryway
Document Recent Improvements
Gather documentation of any recent renovations or upgrades you've made. Receipts, permits, and before-and-after photos can demonstrate the value added to your home. Major improvements like a new roof, updated HVAC system, or kitchen renovation should be highlighted.
Prepare the Interior
Clean and organize your home thoroughly. Appraisers need access to all areas, including:
- Attics and crawl spaces
- Basements and mechanical rooms
- Closets and storage areas
- All bathrooms and bedrooms
Provide Relevant Information
Be ready to share information about your property, such as square footage, lot size, age of major systems, and any recent repairs or upgrades. This information helps appraisers make accurate assessments.
Addressing Low Appraisals and Next Steps
Sometimes a home appraises for less than expected. Understanding your options is important.
Understanding Why the Appraisal Came in Low
Request a detailed explanation from the appraiser or lender. Common reasons for low appraisals include:
- Comparable sales used were from properties in declining neighborhoods
- Recent market downturn affecting property values
- Deferred maintenance or needed repairs
- Appraisal errors or incomplete property assessment
Requesting an Appraisal Review
If you believe the appraisal is inaccurate, you can request a review. Provide additional comparable sales data, documentation of recent improvements, or evidence of appraisal errors. Some lenders allow for a second appraisal if the first one seems questionable.
Negotiating or Adjusting Your Strategy
If you're selling, a low appraisal may require price negotiations with the buyer. If you're refinancing, you might need to increase your down payment or explore alternative lending options. Work with your real estate agent or lender to determine the best course of action.
"A professional appraisal provides an objective assessment of your home's value, protecting both buyers and lenders in the transaction process."
Moving Forward
Whether your appraisal meets expectations or comes in lower than anticipated, remember that it's just one factor in the real estate transaction. Focus on understanding the assessment, addressing any legitimate concerns, and making informed decisions about your property's future.
